BlockFi and FTX Ink $250 Million Revolving Credit Agreement
BlockFi, a cryptocurrency firm, signed a $250 million revolving credit agreement with FTX, a major cryptocurrency exchange. According to Zac Prince, BlockFi’s Chief Executive Officer, the credit facility provides them wi...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.

BlockFi, a cryptocurrency firm, signed a $250 million revolving credit agreement with FTX, a major cryptocurrency exchange. According to Zac Prince, BlockFi’s Chief Executive Officer, the credit facility provides them with access to capital that ‘further bolsters our balance sheet and platform strength’.
With the agreement, BlockFi will be able to access capital during a rout in the digital currency market. The company announced last week that it would reduce its headcount by about 20%, as well as reduce its marketing spend and executive compensation.
“The proceeds of the credit facility are intended to be contractually subordinate to all client balances across all account types (BIA, BPY & loan collateral) and will be used as needed. Throughout the market volatility of the last several weeks, I’m incredibly proud of how our team, platform and risk management protocols have performed. Today’s landmark announcement reinforces BlockFi’s commitment to serving its clients and ensuring their funds are safeguarded,” Prince commented.
He added: “This agreement also unlocks future collaboration and innovation between BlockFi & FTX as we work to accelerate prosperity worldwide through crypto financial services. This is a significant step forward in our commitment to the strength and accessibility of crypto markets.”
The US Securities and Exchange Commission (SEC) fined BlockFi $100 million in February this year for its high-yield interest accounts that were deemed security products. According to a New York Post report citing sources with direct knowledge of the negotiations, FTX has withdrawn from discussions with MLB outfit Los Angeles Angels to offer a jersey patch.
Crypto LayoffsLast week, Coinbase announced that it was pruning its workforce by 18% in preparation for a recession it says could lead to another crypto winter. Two weeks earlier, Gemini said it was cutting its staff base by 10%, citing “current macroeconomic and geopolitical turmoil.” In addition, Crypto.com said it was letting go of 260 workers, or 5% of its corporate workforce.
This article was written by Felipe Erazo at www.financemagnates.com.Why this matters
This cryptocurrency story adds another data point to the current market tape and is useful when read alongside nearby source coverage.
Original source
Read on Finance MagnatesRelated market context
Avalanche onchain credit volume hits record $37.4 million in Q3
Avalanche's record onchain credit growth highlights its potential in institutional finance, but sustainability depends on continue...
Samsung Wallet Brings USDC Transfers to 82 Million US Galaxy Devices in Late October
Samsung announced Oct. 7 that eligible Galaxy users in the US will be able to send USDC from Samsung Wallet starting in the last w...

Avalanche Tokenized Treasury Market Reaches $545 Million After Rapid Growth
TL;DR: Tokenized US Treasury assets on Avalanche have reached roughly $545 million, according to data highlighted this week. The s...
US government moves $470 million in seized crypto to Coinbase wallets, raising Bitcoin sale questions
The US government moved about $470 million in seized crypto to likely Coinbase Prime addresses, according to Arkham, reviving ques...
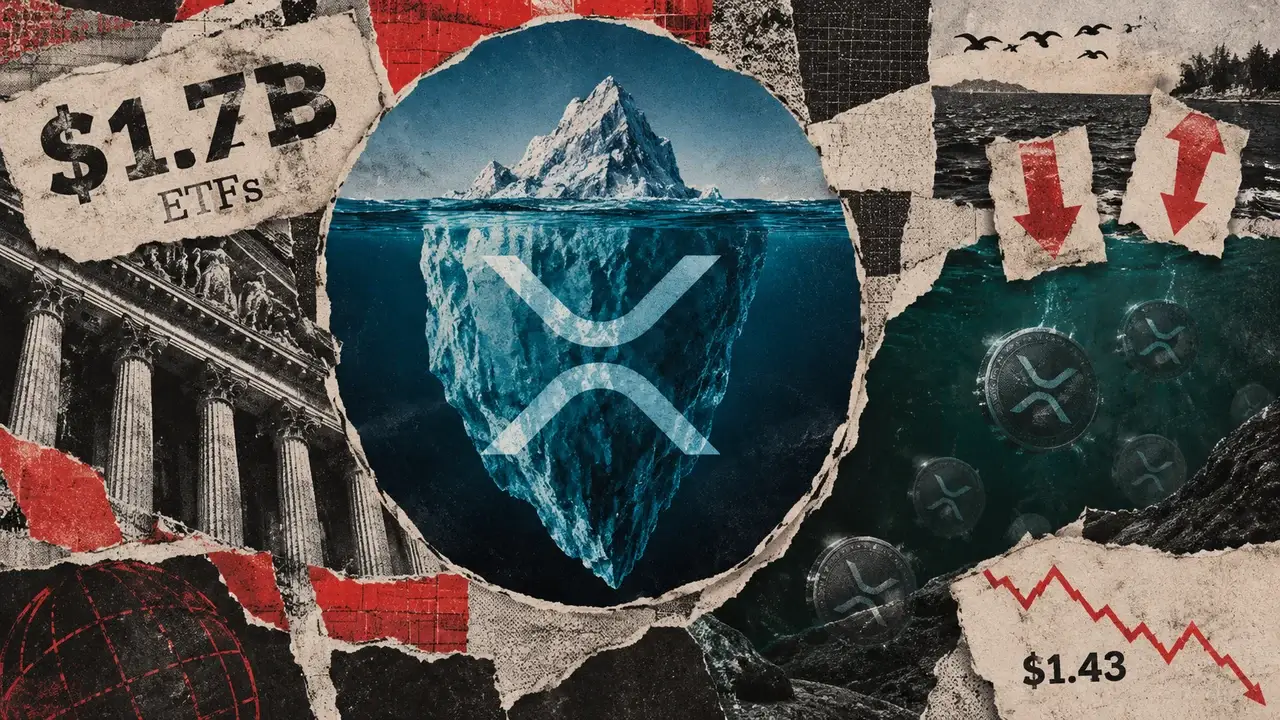
XRP ETFs now hold $1.7 billion but took in just $4M last week
XRP traded around $1.43 on Oct. 7, down 5.46% over 24 hours. Five tracked US spot XRP ETFs held an estimated $1.7 billion at the p...

XRP Whales Dominate Exchange Outflows as Bitcoin Shorts Rise on Hyperliquid
The contrasting flows highlight a market where some large investors are moving XRP away from exchanges even as leveraged traders p...