India’s local crypto exchanges get just 0.7% of inflows, Chainalysis reports
India’s crypto users send substantial value to centralized exchanges, but domestic platforms receive just 0.7% of exchange value in Chainalysis’s new regional report. Its Brazil chapter puts Brazil-based exchanges at 12....
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
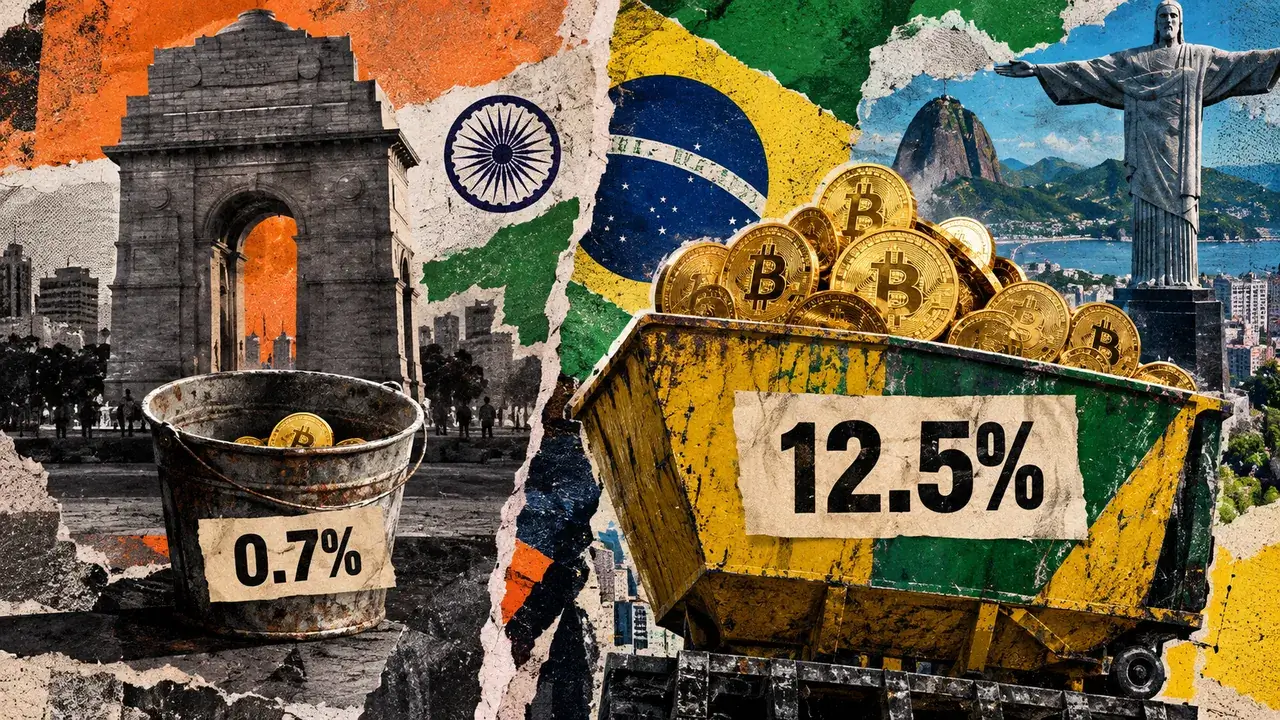
India’s crypto users send substantial value to centralized exchanges, but domestic platforms receive just 0.7% of exchange value in Chainalysis’s new regional report. Its Brazil chapter puts Brazil-based exchanges at 12.5% of inflows.
The contrast separates two business questions that adoption figures can blur: how much activity is associated with a country, and how much its domestic platforms capture. India’s transaction withholding can reduce the cash available for another trade. Its role in venue choice remains an operator explanation, rather than a measured cause of the split.
The findings appeared in Chainalysis’s CSAO chapter on Sept. 30 and Latin America chapter on Sept. 23. Their main annual reporting window runs from July 2025 through June 2026, while the share observations’ precise dates remain unspecified in the chapters’ prose. The new publications describe earlier activity, ending before October.
Chainalysis attributes $88.4 billion in centralized-exchange inflows to India-based users during that annual period, making India the largest such market in Central and Southeast Asia and Oceania. That activity can reach platforms based abroad.
The Indian chapter reports that domestic platforms’ share of exchange value received fell from around 7% to 0.7%, with a sharp decline in mid-2022. Brazil’s chapter describes a different trajectory: Brazil-based exchanges previously received 1.5% of inflows and now receive 12.5%.
Those percentages describe received value in Chainalysis’s exchange analysis. Executed trades, revenue and customer numbers measure other parts of a platform’s business. One deposit can fund subsequent trading, so the amount entering an exchange and the activity inside it answer different questions.
Whether the platform sample stayed unchanged also remains unspecified. The reported divergence supports a descriptive comparison; a synchronized annual market-share comparison would require matching dates and samples.
Brazil’s broader crypto economy recorded $252.5 billion in activity in the year ending June 30, despite contracting 1.6%. That total combines several kinds of activity and has a different scope from exchange inflows. An annual domestic-exchange dollar estimate for either country would require a share and inflow total with matching windows, samples and denominators.
Chainalysis’s general 2026 methodology assigns pooled service activity to user countries using website traffic. For that allocation, it adjusts traffic shares for income differences using the square root of GDP per capita. The chapters leave the detailed calculation of the domestic exchange shares unspecified.
The country assignment follows estimated users. This allows activity at an exchange based abroad to contribute to India’s measured market, while domestic platforms receive a small reported slice.
Chainalysis acknowledges that removing VPN and bot traffic is imperfect. The figures are estimates of geographically attributed activity, with that uncertainty built into the comparison.
Related Reading Crypto’s bear market wiped out over $2 trillion, yet on-chain activity held above $9 trillion Withholding changes the cash available for another tradeIndia’s current section 393 sets 1% withholding on consideration for a virtual digital asset transfer paid to a resident, subject to applicable exemptions. The responsible payer deducts at the earlier of credit or payment.
The base matters: consideration is the amount paid for the transfer. Withholding is calculated against that amount, so a deduction can reduce available proceeds even when the transaction produces little gain.
Consider a ₹100,000 cash sale with consideration paid to a resident seller subject to the standard 1% deduction. Before fees or other adjustments, the seller receives ₹99,000, with ₹1,000 withheld toward tax. That ₹1,000 cannot immediately fund another purchase.
Another liable sale can generate another deduction, adding to the amount already withheld. The final tax calculation determines how those deductions are credited, while each applicable deduction reduces the proceeds immediately available.
The current Act’s exemptions depend on the payer and tax-year aggregate consideration. The limit is ₹50,000 for eligible individuals or Hindu undivided families, including those without business or professional income. Eligibility also covers the stated prior-year business turnover ceiling of ₹1 crore or professional receipts ceiling of ₹50 lakh. Other payers have a ₹10,000 limit.
The limits apply to the tax-year aggregate. Their relevance depends on the payer’s circumstances, so checking eligibility comes before applying the general rate.
Who handles the deduction also matters. The statutory obligation belongs to the responsible payer. The department’s historical section 194S guidance separately explains buyer responsibilities in direct transactions and exchange responsibilities in relevant exchange settlements.
The department’s VDA tax-certificate FAQ explains that the deductee can claim TDS credit when filing a return. The Act allows a refund where tax paid exceeds tax due, with a return claim required.
For traders and platforms, tax credit and trading cash therefore work on different timelines. A deduction can offset tax while reducing immediately available proceeds. The transition guidance explains how credits follow the relevant tax period; it supplies no fixed refund waiting time.
CoinSwitch co-founder Ashish Singhal told Chainalysis that tax friction helps explain offshore use, adding that foreign venues may not make the deduction. That is an operator’s account of the competitive pressure facing compliant exchanges.
How much withholding contributed to the reported share decline remains unmeasured. Foreign platforms may comply with Indian obligations, and a platform’s location alone supplies no blanket exemption. Singhal’s explanation identifies a plausible competitive pressure while leaving its contribution to the measured outcome open.
Related Reading India moves to block 15 crypto apps, leaving users facing sudden account lockout Payment access extends across local and international venuesFiat access offers another possible part of the explanation. Mercado Bitcoin describes a Pix route for buying cryptocurrency from a customer’s bank app. That connects a familiar payment service with crypto access.
An INR buying explainer from CoinSwitch describes deposits through UPI and net banking on platforms operating in India. The generic explainer shows how local currency access can work in India; availability depends on the platform and supported method.
International competition can use local rails as well. Binance’s BRL deposit guide describes Pix and TED transfers. These examples show local payment routes appearing in both domestic and international offerings.
Chainalysis presents regulatory clarity, investment and stronger local offerings as possible explanations for Brazil’s growing domestic share. Its industry interviewees also describe corporate stablecoin use for liquidity and cross-border transfers. Such demand could give platforms opportunities beyond investment trading. Its effect on domestic venue choice remains a hypothesis: the product pages document offerings, while the interviews describe industry experience.
Related Reading Brazil’s $252 billion crypto market gets $10,000 self-custody reporting ruleIndia’s large attributed exchange market can coexist with a small domestic-platform foothold. Brazil’s reported domestic gain shows a different pattern. For operators, the destination of exchange inflows remains a distinct question from the size of national participation.
The post India’s local crypto exchanges get just 0.7% of inflows, Chainalysis reports appeared first on CryptoSlate.
Why this matters
Chainalysis is showing up inside the Market Structure theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context

XRP Whales Dominate Exchange Outflows as Bitcoin Shorts Rise on Hyperliquid
The contrasting flows highlight a market where some large investors are moving XRP away from exchanges even as leveraged traders p...

Non-Custodial Crypto Exchanges: How Self-Custody Is Changing the Way Users Swap Digital Assets
For many users, the distinction comes down to custody. A centralized platform may hold assets on behalf of its customers, while a...
NEAR’s Polosukhin sees shrinking need for centralized exchanges as onchain tools expand
NEAR co-founder Illia Polosukhin said users no longer need centralized exchanges for "a lot" of crypto activity.
CFTC proposes federal registration for crypto exchanges offering leverage
The proposed CFTC regulations could reshape U.S. crypto markets by reducing high-leverage options, aligning them with traditional...

BTCC Exchange Launches Refreshed Trust Center: Alex Hung on 15 Years of Earning Traders’ Trust
GEORGE TOWN, Cayman Islands, October 7th, 2026, Chainwire BTCC, the world’s longest-serving cryptocurrency exchange and Platinum S...
CFTC Chair Says New Crypto Rulemaking Will Prevent Another FTX-Style Collapse
Bitcoin Magazine CFTC Chair Says New Crypto Rulemaking Will Prevent Another FTX-Style Collapse Pro-crypto regulator Mike Selig has...