FDIC moves to eradicate ‘reputational risk’ category from bank exams
The US Federal Deposit Insurance Corporation, an independent agency of the federal government, is reportedly moving to stop using the “reputational risk” category as a way to supervise banks. According to a March 24 lett...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
The US Federal Deposit Insurance Corporation, an independent agency of the federal government, is reportedly moving to stop using the “reputational risk” category as a way to supervise banks.
According to a March 24 letter sent by the agency’s acting chairman, Travis Hill, to Rep. Dan Meuser, banking regulators should not use “reputational risk” to scrutinize firms.
“While a bank’s reputation is critically important, most activities that could threaten a bank’s reputation do so through traditional risk channels (e.g., credit risk, market risk, etc.) that supervisors already focus on,” notes the letter, first reported by Politico.
According to the document, the FDIC has completed a “review of all mentions of reputational risk” in its regulations and policy documents and has “plans to eradicate this concept from our regulatory approach.”
Reputational risk and debankingThe Federal Reserve defines reputational risk as “the potential that negative publicity regarding an institution’s business practices, whether true or not, will cause a decline in the customer base, costly litigation, or revenue reductions.”
The FIDC letter specifically mentioned digital assets, with Hill noting that the agency has generally been “closed for business” for institutions interested in blockchain or distributed ledger technology. Now, as per the document, the FDIC is working on a new direction for digital asset policy aiming at providing banks a way to engage with digital assets.
The letter was sent in response to a February communication from Meuser and other lawmakers with recommendations for digital asset rules and ways to prevent debanking.
Industries deemed as “risky” to banks often face significant challenges in establishing or maintaining banking relationships. The crypto industry faced such challenges during what became known as Operation Chokepoint 2.0.
The unofficial operation led to more than 30 technology and cryptocurrency companies being denied banking services in the US after the collapse of crypto-friendly banks earlier in 2023.
Related: FDIC resists transparency on Operation Chokepoint 2.0 — Coinbase CLO
Why this matters
This cryptocurrency story adds another data point to the current market tape and is useful when read alongside nearby source coverage.
Original source
Read on CointelegraphRelated market context
Stablecoin transfers quadruple to $891B as US banks adopt technology
The surge in stablecoin transfers highlights a shift towards digital finance, potentially reshaping global banking and economic dy...
112M Americans want crypto services from banks, NCA poll finds
The growing demand for crypto services in banks highlights a potential shift in financial landscapes, urging banks to adapt or ris...
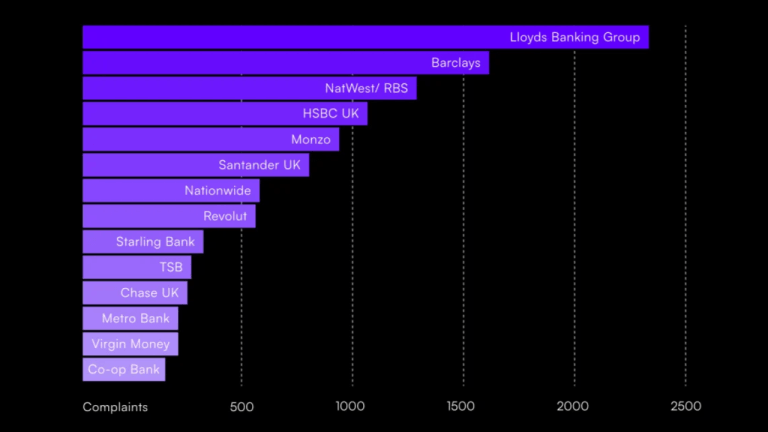
UK Banks Flooded With Crypto User Complaints, Led by Lloyds and Barclays
Evidence of banks restricting services for crypto asset users keeps piling up on both sides of the Atlantic. A new report highligh...
Stablecoin transfers quadruple to $891B as US banks expand adoption: Report
Coinbase reports growing adoption by banks and businesses, even as stablecoin market capitalization remains largely unchanged over...
Anchorage Digital partners with Securitize to bring federally issued stablecoins to tokenized assets
This partnership enhances the integration of blockchain in traditional finance, potentially increasing institutional adoption of d...
Mastercard Launches Stablecoin Security to Screen Risk Before Funds Move Onchain
Key Takeaways: Mastercard released Stablecoin Security for assisting banks to identify fraud and sanctions/malicious activities be...