Cardano and Solana just exposed crypto governance’s biggest weakness
Cardano and Solana are testing two competing approaches to on-chain governance, with one exposing the cost of voter absence and the other shifting more power to default representatives who may have their own economic int...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
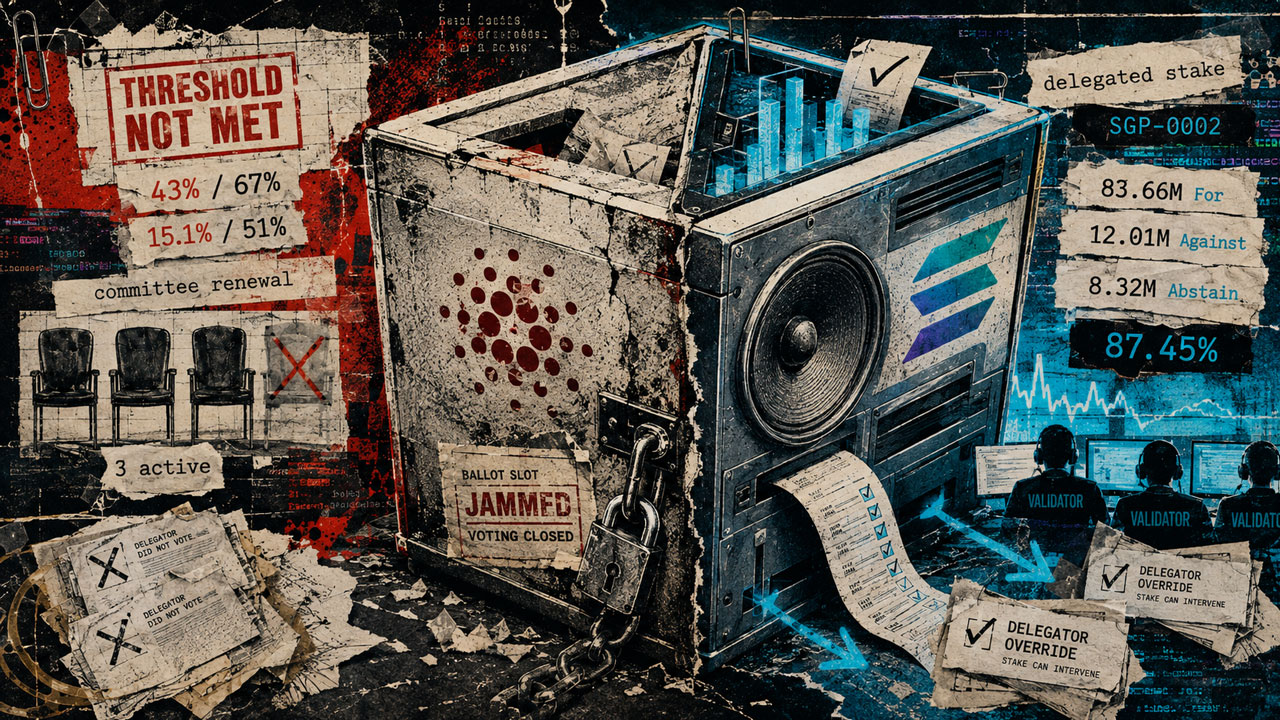
Cardano and Solana are testing two competing approaches to on-chain governance, with one exposing the cost of voter absence and the other shifting more power to default representatives who may have their own economic interests.
Cardano’s constitutional committee renewal requires separate approval from delegated representatives, or DReps, and stake pool operators. Solana instead allows validators to cast governance votes using the active stake delegated to them unless individual stakers override that choice.
The distinction is becoming visible in simultaneous votes on both networks.
Cardano faces the more immediate risk. An Aug. 26 snapshot showed support for its committee renewal below the required thresholds among both DReps and stake pool operators, creating the possibility that four committee terms expire without replacements.
Solana reduces that kind of participation bottleneck by making validators default voting agents. But its current governance vote shows the tradeoff: stakers who do nothing effectively allow validators to exercise governance weight associated with their delegated stake, even when those validators may have financial interests affected by the proposal.
Both systems therefore confront the same underlying problem from different directions. Cardano leaves inactive voters silent. Solana lets an existing delegate speak for them.
Cardano’s governance risk is already measurableA DRepTalk snapshot accessed Aug. 26 showed Cardano’s Update Constitutional Committee 2026 proposal with 43% DRep support, below the required 67%, while stake pool operator support stood at 15.1% against a 51% threshold.
Each group must independently clear its requirement. Stronger participation by one cannot offset a shortfall in the other.
The vote carries a fixed consequence because four committee terms expire at epoch 799, while the maximum allowable term length means replacements must be enacted in epoch 653. Published material identifies Sept. 1 as the relevant deadline.
If the proposal fails, Cardano would be left with three active constitutional committee members, below the reported five-member minimum required for committee-dependent governance actions.
Related Reading Cardano has two weeks to avoid a governance freeze as 4 committee seats expireThat would not stop block production or freeze the entire network. It would, however, leave the committee unable to ratify actions that require its approval until governance restores sufficient membership.
Intersect has warned that such a disruption could affect the timing of the Dijkstra upgrade, though that does not automatically cause a delay.
Cardano’s design makes the cost of inaction explicit. Its governance system requires two separate constituencies to express enough support, preserving each group's independence while also creating two opportunities for insufficient participation to block continuity.
Solana reduces turnout risk, then inherits an agency problemSolana’s model lowers the participation burden by allowing validators to vote with the stake already delegated to them.
Eligible stakers can override a validator’s choice for an individual stake account. When they do, that stake is removed from the validator’s effective tally and applied directly to the staker’s own selection.
That mechanism was active during SGP-0002, a proposal seeking support for faster SOL disinflation.
An Aug. 26 Validator Info snapshot showed 83.66 million SOL voting For, 12.01 million Against, and 8.32 million Abstain. Among decisive votes, support stood at 87.45%.
Direct delegator overrides were visible but small compared with the roughly 104 million SOL represented in the tally. Validator Info listed 308 delegator voters, with only a fraction of the overall voting weight directly reassigned.
The override mechanism is therefore being used. The current vote does not yet show whether large numbers of passive delegators would intervene when they disagree with their validator.
That question becomes more significant when validators have an economic stake in the policy under consideration.
Solana Company, a publicly traded SOL treasury firm, said it opposed SGP-0002 on timing and policy-stability grounds. Its second-quarter filing showed $2.512 million in staking revenue out of $2.526 million in total revenue, meaning staking accounted for about 99.4% of quarterly revenue.
The proposed policy would accelerate annual disinflation from 15% to 30%, reducing projected issuance by about 18.9 million SOL over six years and bringing the network to its 1.5% terminal inflation floor in roughly 2.8 years instead of 5.7 years.
Those facts establish an economic exposure, but they do not prove misconduct or that financial incentives determined the company’s vote. Stakers also retain the ability to override validator choices.
Solana’s rule conflict adds another layer of uncertaintyThe Solana vote is complicated further by conflicting public descriptions of what constitutes passage.
The Solana governance FAQ says one-third of network stake must participate and two-thirds of participating stake must vote For. The governance proposal repository instead says there is no quorum requirement and that For must receive two-thirds of For plus Against, excluding Abstain.
Under the repository rule, the observed vote clears the support threshold. Under the FAQ and Validator Info display, participation remained below the one-third line.
That leaves the same tally open to two different interpretations and makes the result difficult to assess until the applicable rule is reconciled.
Even a favorable result would not immediately change SOL issuance. SGP-0002 would establish policy direction, while the underlying SIMD-0550 proposal would still need to move through implementation before any consensus-affecting change could be activated.
Both systems relocate the cost of voter apathyThe current votes show that delegation changes the form of participation risk rather than removing it.
Cardano bears the cost directly when voters fail to show up. Its immediate danger is concrete: two constituencies remain below required thresholds ahead of a fixed deadline, with committee capacity at stake.
Solana reduces that risk by allowing validators to represent passive holders, but the model shifts more responsibility toward oversight. Delegators must monitor the agents voting with their stake and intervene when their preferences diverge.
Cardano therefore faces a clearer near-term governance threat, while Solana raises a longer-term question about representation and incentive alignment.
The next results will sharpen that contrast. Cardano must determine whether DReps and stake pool operators can mobilize before the committee deadline, while Solana still needs to establish which voting rule governs SGP-0002 and how much weight delegator overrides ultimately carry.
Both systems arrive at the same unresolved question from opposite directions: whether on-chain governance can remain effective when most tokenholders prefer not to participate.
The post Cardano and Solana just exposed crypto governance’s biggest weakness appeared first on CryptoSlate.
Why this matters
Cardano is showing up inside the DeFi theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context
Charles Hoskinson says Cardano no longer comes first – its treasury vote explains why
Cardano's delegated governance voters let a 12.29 million ADA request for Pogun expire without ratification, showing that Input Ou...
3-year-old bug triggers $1.3 million drain and forces 10-day blockchain halt
A routine Radix code refactor created a vault flaw that enabled a roughly $1.3 million theft and later forced validators to halt t...
ZetaChain votes to shut down Layer 1 network, migrate ZETA to Solana
ZetaChain's shift to Solana reflects a strategic pivot towards AI, altering its market identity and impacting investor expectation...
EU staking review threatens crypto yields and network security could pay the price
Some of the most consequential financial rules begin with surprisingly little text. For example, on page 36 of the European Commis...
ZEC’s 100% rally above $1500 sends Grayscale’s Zcash ETF within $85 million of $1 billion
Grayscale’s Zcash ETF is closing in on $1 billion in assets less than a month after its Wall Street debut. The fund, which trades...
Anthropic’s potential $2 trillion IPO is fueling an $80 million crypto trade
Anthropic’s prospective $2 trillion IPO has already spawned nearly $80 million in crypto derivatives bets before its public debut....