Bitcoin turned $10,000 into $870,000 in a decade where 87% of active stock funds failed to beat passive rivals
Bitcoin returned 87 times over a decade, while only 13% of actively managed US large-cap equity funds beat comparable passive funds' benchmarks through June 30, according to Morningstar data reported by The Wall Street J...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
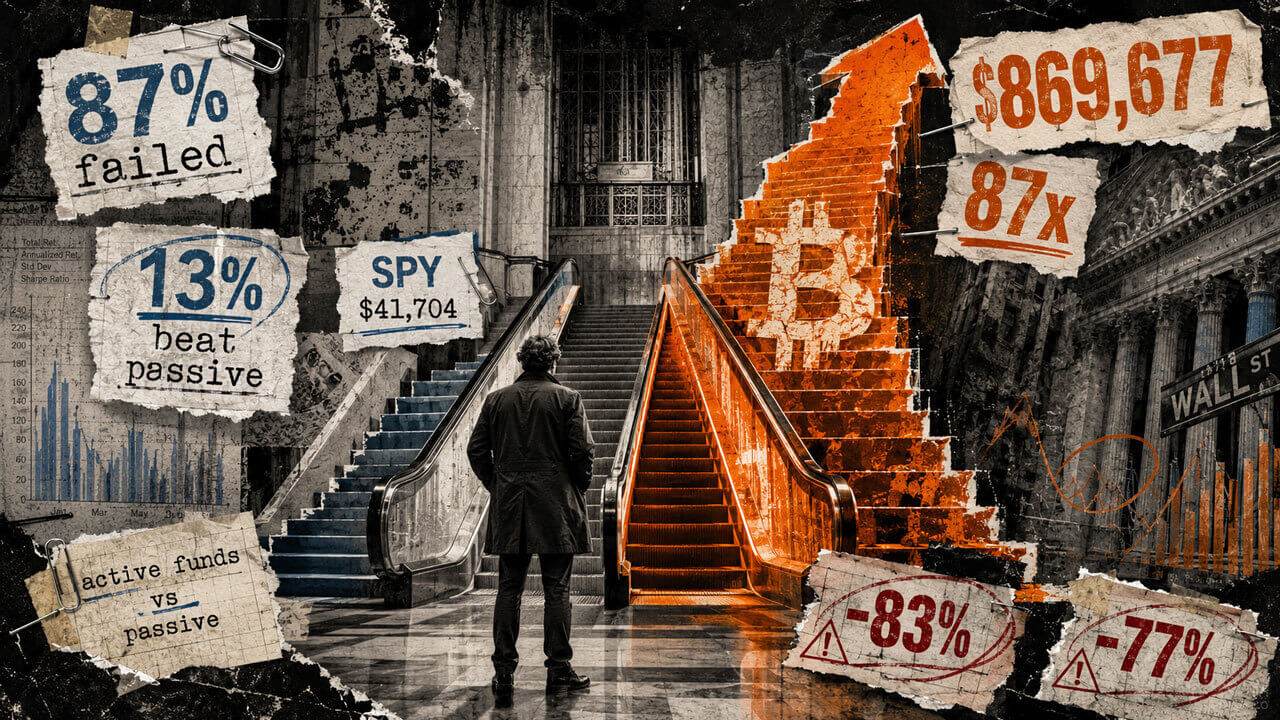
Bitcoin returned 87 times over a decade, while only 13% of actively managed US large-cap equity funds beat comparable passive funds' benchmarks through June 30, according to Morningstar data reported by The Wall Street Journal.
That rate rose to 27% over the latest 12 months, and Wall Street has argued that AI-driven dispersion and higher interest rates should give stock pickers more room to outperform.
Bitcoin closed at $673.34 on June 30, 2016, and closed at $58,558.86 on June 30, 2026. This means a $10,000 position in the top crypto will grow to about $869,677.
That equals roughly 87 times the original capital and an 8,597% total return, resulting in Bitcoin compounding at about 56.3% a year over the period.
State Street lists SPY’s 10-year annualized total return at 15.35% through June 30, with distributions reinvested. A $10,000 investment compounded at that rate reached about $41,704, and Bitcoin finished with about 20.9 times the final wealth.
Related Reading SEC approves spot Bitcoin ETFs after 11 years of rejections After over a decade of hesitation, the SEC's green light for spot Bitcoin ETFs signals a new era for crypto in mainstream finance. Jan 10, 2024 · Assad JafriFund mandates kept most active large-cap managers inside equities, since US spot Bitcoin ETFs arrived only in 2024. Investors made the broader comparison at the portfolio level, where capital could move across asset classes.
Investors spent years deciding whether professional stock selection could earn enough excess return to justify its fees. A separate allocation to Bitcoin generated a far larger dollar outcome for holders who endured its volatility.
Asset / category Starting point Ending value Total return What it shows Bitcoin $10,000 ~$869,677 ~8,597% One asset-allocation call produced an 87x outcome SPY, distributions reinvested $10,000 ~$41,704 ~317% Passive U.S. equity exposure compounded strongly, but far below BTC Active large-cap funds 13% beat passive rivals 87% failed to beat N/A Most stock-picking funds lagged comparable passive alternatives The stock picker’s market faces BitcoinS&P 500’s 10 biggest members represent more than 40% of its weight, according to Dow Jones Market Data, the highest concentration since the 1960s.
Market cap weighting automatically gives more weight to companies as their valuations climb, so a diversified active manager can trail the benchmark by holding smaller positions in the stocks already driving index returns.
Wide dispersion gives managers more chances to identify winners, while extreme concentration raises the cost of missing a few dominant names. A manager can make several successful selections and still trail an index powered by a small group of mega-cap companies.
The benchmark absorbs more exposure to its strongest constituents as their market values expand. Active managers have to decide how closely their portfolios should resemble that concentration.
Market condition Why it should help active managers Why it still favored passive indexes High stock dispersion More winners and losers to select from Missing the biggest winners became more costly S&P 500 concentration Creates clear leaders to overweight Top 10 stocks made up more than 40% of the index Market-cap weighting Automatically rides rising winners Passive funds increased exposure as winners grew Diversification limits Reduces single-stock risk Can leave active funds underweight the stocks driving returnsA Bitcoin holder made one asset-allocation decision and carried that exposure through an entire decade. The return depended heavily on surviving losses that would breach many conventional portfolio limits.
Wells Fargo notes that Bitcoin fell about 83% from its 2017 peak, and later fell about 77% from its 2021 peak. A holder seeking the full 87x decade return had to absorb both collapses without abandoning the position.
Those drawdowns make the historical result harder to replicate in real time than the final numbers imply. Bitcoin also carried custody, liquidity, tax, and portfolio-risk characteristics far removed from SPY or a diversified large-cap fund.
Related Reading Bitcoin ETFs built a powerful bid, but the same machine can now accelerate selling Spot Bitcoin ETFs have widened access to BTC, but the same flows that support price can reverse quickly when macro pressure rises. Apr 29, 2026 · Gino MatosICI reported $18.8 trillion in active mutual funds and ETFs as of June 2026, with indexed mutual funds and ETFs holding nearly $21.9 trillion. Long-term active funds recorded $7.78 billion of net outflows, and long-term index funds attracted $119.32 billion.
Those numbers show how investors have already weighed in on the active-versus-passive debate. Passive products have captured more assets and new money as most large-cap active funds struggle to clear their benchmarks over long periods.
Bitcoin adds an asset-allocation dimension to that debate, with the decade’s largest difference in this comparison coming from exposure to another asset class. Manager selection inside US equities operated within a much narrower range of outcomes.
Two paths for active managersThe bull case for active management depends on equity gains broadening beyond the largest companies. A wider group of AI beneficiaries and sector leaders would give managers more opportunities to exploit dispersion.
Broader participation would also reduce the penalty for holding smaller weights in the index’s dominant stocks.
Related Reading AI stock concentration flashes dot-com warning as Bitcoin miners’ pivot faces test AI exposure has become a balance-sheet test for miners that sold investors on HPC growth before Bitcoin gets any relief. Apr 29, 2026 · Liam 'Akiba' WrightThe bear case keeps benchmark concentration near current extremes. Passive funds would continue increasing their exposure to winners as market values climb. Active managers with tighter diversification limits could keep falling behind whenever a few mega-cap names account for an outsized share of index returns.
Scenario What happens in equities What happens to Bitcoin Read-through Active bull case AI gains broaden beyond mega-cap leaders BTC remains a separate allocation story Stock pickers get more room to outperform Passive dominance case Index concentration stays extreme BTC comparison keeps highlighting allocation over selection Passive funds keep benefiting from mega-cap momentum Bitcoin endurance case Equity returns remain narrower BTC holds long-term gains despite volatility Portfolio allocation matters more than manager selection Bitcoin drawdown case Active/passive debate continues inside equities BTC suffers another major cycle decline The 87x result looks harder to repeat in real timeAnother deep drawdown for Bitcoin could erase years of gains for buyers who enter near a cycle peak. The 2017 and 2021 collapses show how much endurance the historical return required.
Investors who held Bitcoin through two drawdowns near 80% finished the decade with roughly $828,000 more than the equivalent SPY position. That outcome puts the scale of portfolio allocation beside the narrower fight over who can pick stocks well enough to beat an index.
The post Bitcoin turned $10,000 into $870,000 in a decade where 87% of active stock funds failed to beat passive rivals appeared first on CryptoSlate.
Why this matters
Bitcoin is showing up inside the Regulation theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context
After Congress killed its landmark crypto bill, the SEC unlocked the $77 trillion US stock market through tokenization
The US Securities and Exchange Commission (SEC) has opened a five-year pathway for regulated US stocks to trade on blockchain-nati...

Zoomex Highlights Key ETF Market Trends Ahead of This Week’s Federal Reserve Decision
VICTORIA, Seychelles, September 16, 2026 Global markets are entering a high volatility stretch. With a Federal Reserve rate decisi...
Crypto Stocks Paid for the Clarity Act’s Failure. Does Bitcoin Pay Next?
The Clarity Act died on Tuesday. The Senate voted 49 to 50—short of the 60 needed to even start debate, with zero Democrats voting...
SEC Clears Path for Tokenized Stocks With 5-Year Onchain Trading Exemption
Key Takeaways: The SEC has introduced a five-year “Innovation Exemption” to permit trading of U.S. stocks by tokenizing them on ap...
Crypto.com Can List Single-Stock Futures in the US Without Waiting for SEC Approval
Crypto.com‘s futures exchange became a registered national securities exchange for security futures products the moment it filed f...

Crypto Tokenized Stocks Gain a Temporary SEC Pathway After Senate Setback
The Senate failed to advance the CLARITY Act on September 15, with the crypto market-structure bill falling to a 50-49 vote, 10 sh...