Can the First Couple of Blockchain Deliver a Second Act for Tezos?
Kathleen and Arthur Breitman are crypto royalty. The husband-and-wife team created Tezos, an early leader in the “second generation” of blockchains, and are the authors of an influential series of essays on crypto govern...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
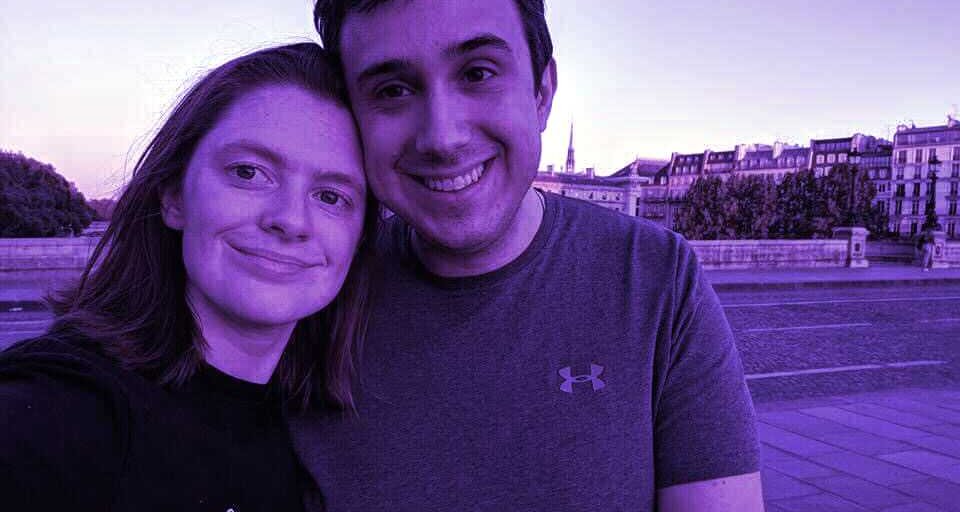
Kathleen and Arthur Breitman are crypto royalty. The husband-and-wife team created Tezos, an early leader in the “second generation” of blockchains, and are the authors of an influential series of essays on crypto governance.
In 2016, the pair raised an eye-popping $232 million for Tezos in an initial coin offering, putting the project—which was among the first to incorporate now-familiar crypto concepts like proof-of-stake—in a position to lead the crypto industry. But then something happened: the blockchain built by the Breitmans fumbled its early lead and Tezos was surpassed by Ethereum and other rivals that offered similar features.
Once near the top of cryptocurrency price rankings, Tezos’ XTZ token sunk this year to number 40, far behind novelty coins like Doge and also-rans from the first generation of crypto.
Now, Tezos is in a fight for relevance—as Kathleen herself acknowledges. “There are thousands of blockchains but the ones that matter will be ‘winner take most’ with the top three taking 90% of the market,” she says.
Can Tezos make a comeback? Skeptics think the window may have closed as Ethereum consolidates its dominance, and as newer projects like Solana climb up the crypto charts. But the Breitmans, who are resuming a more active role after leaving the guidance of Tezos to others, argue the real competition for blockchain dominance is just beginning.
The first couple of blockchainThe Breitmans are in their thirties, but come across as long-tenured academics. Arthur is French with a world-weary affect and can describe any aspect of blockchain, no matter how technical, with quick precision. Kathleen, who grew up in New York City, is equally versed in crypto but likes to spice up her accounts with gossip and droll anecdotes. The pair met at Cornell where their mutual passion for polymath study led them to marriage and to the blockchain project that made them minor celebrities.
The Breitmans first published their vision for Tezos in 2014, five years after Satoshi introduced Bitcoin to the world. By this time, Bitcoin’s potential had become clear—the currency crossed the once-unthinkable $1000 mark in late 2013—but so too had its drawbacks. Those include a congested network, limited features, and an unruly governance structure that makes significant reforms nearly impossible.
The Tezos blockchain promised to overcome these problems. One of the first of a “second generation” of blockchains—Ethereum and Polkadot are among the others—the Breitmans’ blockchain promised a more efficient way to process transactions through a now familiar mechanism called proof of stake. It also touted a version of smart contracts, which made Tezos infinitely more versatile than Bitcoin, and a democratic governance structure that allowed token owners to vote on changes to the network. This voting system also introduced a novel delegation idea called staking that has since been imitated by other blockchains.
Tezos also stood out because its creators, unlike other blockchain builders, didn’t attempt to cultivate larger-than-life personas or embrace the weirder fringes of meme culture. Arthur, especially, has a distaste for hype—even if that puts him at odds with the broader crypto community.
“I don’t want to be part of that thought leadership crap," he says. "I like nuance. But people don’t want nuance, they want charismatic leaders."
Shunning the cult-of-personality aspect of the crypto scenes, the Breitmans worked on building out their vision for a new type of blockchain and attracted high profile supporters, including the venture capital firm Andreessen Horowitz, which published several of their papers in its “crypto canon” of essential reading.
They also raised money. A lot of it. Amid the crypto hype cycle of 2017, Tezos conducted one of the biggest initial coin offerings of all time, raising $232 million, a good portion of which is still parked in the project’s eponymous foundation.
Then came trouble. Shortly after the ICO, the Breitmans became enmeshed with a slippery European they hired to run the Tezos Foundation but who they say engaged in self-dealing at the expense of Tezos. This led to a bitter legal fight and a delay in the launch of Tezos’ real-life blockchain that triggered new lawsuits from frustrated token buyers.
The Breitmans ultimately prevailed, leading Wired to place them on its cover with the caption “The Blockchain: a love story, a horror story.” (Kathleen gripes that the photos made them look cadaverous.) By 2018, Tezos blockchain had evolved from concept to a live blockchain, achieving the crypto world’s ideal of a global ledger maintained by a decentralized community.
Arthur and Kathleen Breitman on the June 2018 cover of Wired (via: Wired)Having accomplished their dream, the Breitmans moved on to other projects, including a Magic the Gathering style video game that lets players use blockchain to store cards and other digital artifacts.
But somewhere amid all this progress, Tezos lost steam. The value of its tokens began to slide as Ethereum became the dominant smart contract blockchain, and newer projects like Uniswap and Solana enjoyed the hype once lavished on the Breitmans’ creation. On Reddit and other social media platforms, crypto watchers began to ask if Tezos had become a “ghost chain”—a working blockchain with few real world users.
“It felt like it had a large lead initially as one of the older Layer 1 blockchains out there, and had lots of momentum going into 2020. Now it seems like they’re stuck in place,” says Wilson Withiam, an analyst with crypto research firm Messari, who describes Arthur and Kathleen as “brilliant” but questioned whether their creation will last.
Why did Tezos stumble?The lawsuits are the most obvious explanation for Tezos’s fading star. The legal fight for control of the blockchain, in particular, created distraction and delays and took an emotional toll on the Breitmans—Kathleen notes the pandemic has been easy by comparison.
“We already went through the shittiest version of being alone together when we were being sued,” Kathleen says dryly.
But while the legal drama hurt Tezos’ momentum, it’s not the only reason for the project’s stumbles. The blockchain has also been hindered by a lack of developers—the people who build infrastructure and applications, and who are essential to turn a software protocol into a thriving eco-system.
A lack of developers implies a lack of users and, in the case of blockchains, the risk a project will turn into software’s version of a desert. Arthur acknowledges some came to view Tezos this way.
“Back in the spring, Ethereum talking heads were saying ‘Tezos is a ghost chain,’” he notes, but points to a recent uptick in activity on the blockchain to say the claim is unfounded, and that the project has turned a corner.
Still, the challenge over attracting developers persists, especially as Tezos must compete not just with the likes of Bitcoin and Ethereum, but with a host of flashy newer projects like Cosmos and Avalanche.
Adding to the challenge in luring developers is the fact Tezos is written in OCaml, a programming language developed by top coders and the government of France.
Arthur is of the French elite—he attended the country’s grandes écoles and his father is a successful playwright—so it’s no surprise he chose OCaml to create Tezos. But while the language is technically sound, OCaml is also unfamiliar to the vast majority of developers and viewed as difficult. In contrast, Vitalik Buterin chose to build his Ethereum blockchain in an easy-to-use language that is a close off-shoot of the ubiquitous JavaScript. It's a big reason Ethereum has flourished.
Tezos’ technical barriers have slowed its growth but so too did another of its distinctive features—its governance process. That process is designed to be transparent and democratic, but it is also slower than what occurs at other blockchains, where big decisions are typically pushed through by a small clique of insiders.
Ironically, Tezos may have paid a price for achieving decentralization, which is the highest ideal in crypto circles, but which is more often carried out in lip service than in actual practice.
“They did a nice job of holding true to the ethos of decentralization but, when it comes down to it, how much decentralization do users actually want? That’s where the governance process, as interesting as it is, played to their detriment,” observes Messari’s Withiam.
Withiam notes that newer, more centralized rivals like Solana and Binance have been able to experiment more, and have rolled out major new features in days or weeks—features that would take Tezos, with its meticulous governance process, months or more to push through.
Defying the DeFi TrendTezos’s slow response to new crypto trends was evident when it came to decentralized finance or DeFi, the Lego-like stack of applications that has become the biggest blockchain story of the last two years. The primary beneficiary has been Ethereum, where investors have parked hundreds of billions of dollars in DeFi smart contracts, but Binance, Solana and others have partaken in the boom too.
Tezos, however, sat out the DeFi trend until last month when it launched a modest feature called “liquidity baking” that lets users deploy smart contracts and earn Tezos's token XTZ if they put Tezos or a synthetic version of Bitcoin in a liquidity pool. The move was a grudging acknowledgement by Tezos of DeFi’s relevance—though Kathleen and Arthur maintain the phenomenon is overblown.
“A lot of DeFi projects are going to age like old milk,” says Kathleen, who has special contempt for yield farming—a DeFi phenomenon in which new blockchain projects hand out bonus tokens to those willing to place its other tokens in a liquidity pool. She says yield farming often amounts to a hustle by projects that don’t have any purpose or, worse, are retreads of earlier flops.
“You get all of these use cases from 2015 dusted off and repackaged," she says bitterly. "They claim it's different because it will have a yield-per-week component. ‘But now with yield farming!'"
Arthur is more measured. He views yield farming as a novel fund-raising mechanism that lets new blockchain projects raise capital without turning to traditional investors or to airdrops, which hand out tokens indiscriminately in the hopes people will trade them. But he also warns many yield farming initiatives are empty shells to promote tokens that don’t serve any purpose.
Some of this might sound like sour grapes given that Tezos missed out on the DeFi boom. But the Breitmans aren’t sour towards rivals like Sam Bankman-Fried ("SBF"), The founder of crypto exchange FTX who became crypto’s hottest celebrity of 2021 in part because of the fortunes he made on DeFi.
“With SBF, there's a lot of, 'Damn, that was a good idea,’” says Kathleen. “He's not putting people down, he’s kind of a happy warrior, which makes you want to root for him.”
Maybe so, but SBF’s success and that of Solana, which he has backed, means a further obstacle to Tezos reemerging as a leading blockchain—especially if, as the Breitmans themselves believe, only two or three blockchains will come to dominate crypto in the future.
Tezos Comeback?Kathleen describes herself and Arthur as "grizzled" and says their experience gives them staying power.
Grizzled is an odd way to describe someone who is barely 30, but in a crypto sector that’s just a decade old and full of fresh-faced founders, she may have a point. The Breitmans claim their trials over the last five years leave Tezos in position to win the blockchain race.
The pair claims that the foundations of Tezos are sounder than those of rival blockchains, and that this is something others are beginning to notice.
It’s not an idle claim, as several big brands have embraced Tezos in recent months. Those include Red Bull and McLaren Racing, which are using the blockchain for fan experiences, as well as gaming giant Ubisoft, which is testing Tezos for new video game experiences.
And if Tezos sat on the sidelines for the DeFi boom, it is carving out a major role for itself in a newer crypto mega-trend: the frenzy over non-fungible tokens (NFTs), which let people own unique blockchain-stamped digital artifacts like art or sports highlights.
While most NFT action still happens on Ethereum, Tezos is home to a major NFT marketplace known as “hic et nunc.” The forum was launched by a Brazil developer who received a small grant from the Tezos Foundation, which has been sprinkling money on projects across the globe and finally hit pay dirt.
The blockchain’s NFT reputation gained a further boost when the American music star known as Doja Cat chose OneOf, another Tezos-backed forum, to issue her first NFT. She said her choice was based on environmental concerns since the blockchain doesn’t depend on energy-intensive mining like Ethereum.
Kathleen said in a recent Forbes profile that the Breitmans didn’t conceive of Tezos as a green project—but that she is glad it's gaining that reputation. Tezos’ emergence as an NFT magnet is thus partly a function of luck, but perhaps luck the Breitmans deserve after their blockchain’s earlier misfortunes.
In any case, the flurry of NFT activity has helped Tezos notch a more than 1,000% gain in network activity from last year. And on the Doja Cat news, the price of Tezos’ XTZ token took off, helping it climb back into the top 30 on token leader boards.
Meanwhile, Tezos has taken a major step to address its developer problem. It has decided to branch out from the rarified world of OCaml, and test software development tools in the everyman RUST programming language.
As for the Breitmans, they have taken on a more active role in shepherding their creation. After basically stepping away, Arthur has taken a board seat on the Tezos Foundation—a well-funded group that critics say became a magnet for people looking for plush jobs that demanded little in the way of work or results. In recent months, a person familiar with the group’s activities say Arthur has “cleaned house.” Kathleen has returned to her role of blockchain’s version of a public intellectual, publishing essays and, of course, advocating for Tezos.
The Breitmans’ renewed attention has been a welcome development for the project’s beleaguered token holders, but is no guarantee that Tezos will emerge as a long-term winner amid an increasingly crowded field of blockchains. Despite the project's recent momentum, Tezos still risks forever playing catch-up.
Kathleen is unfazed by such predictions. She argues that as the blockchain industry matures, the winners will be defined by the technical merits, and that this will see Tezos reclaim its role at the front of the pack.
“Chains have been driven by the myth and ethos around them, not the technical differentiation,” she says. “We’re all driving model Ts and someone is going to come along with a Ferrari."
She didn’t say whether it will be the Breitmans or someone else who builds that Ferrari.
Why this matters
This blockchain story adds another data point to the current market tape and is useful when read alongside nearby source coverage.
Original source
Read on DecryptRelated market context

As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.
As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield...
Ethereum Devs Lean Toward Shipping Glamsterdam as Is, Push Hoodi Testnet Decision to Next Week
Ethereum’s core developers leaned toward shipping Glamsterdam, the network’s next hard fork, with its contested gas repricing unch...
Crypto News Today: Bitcoin Price Nears $55K as Ethereum Plunges 10% and XRP Tests $0.87 Support
The November 21 selloff has kept all three cryptocurrencies under pressure, with moving averages indicating sustained bearish mome...

Hyperliquid Monero Crashes? Wagyu-Linked XMR1 Collapses, $13.2M Flows Into Ethereum
A Monero token crashed 99% on Friday after 5.2 million XMR1 tokens moved from a wallet tied to its creator, triggering a massive s...
Ethereum’s Glamsterdam delay reveals a troubling pattern behind its biggest network upgrades
Ethereum's Glamsterdam upgrade has slipped into 2027, exposing a growing disconnect between faster development and the network's a...
Tracy Schuchart: Bitcoin Trading “Like a Risk Asset” as Fed Hikes Loom
▶Bitcoin Magazine Tracy Schuchart: Bitcoin Trading “Like a Risk Asset” as Fed Hikes Loom Tracy Shuchart says Bitcoin’s biggest lon...