The Stablecoin in the Headlines Is Not the Stablecoin I Know
When you scroll through the financial news these days, you meet one stablecoin. The articles describe a digital dollar, a boring token that hugs the greenback, and a shiny new tool for Wall Street. Then you open a DeFi a...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
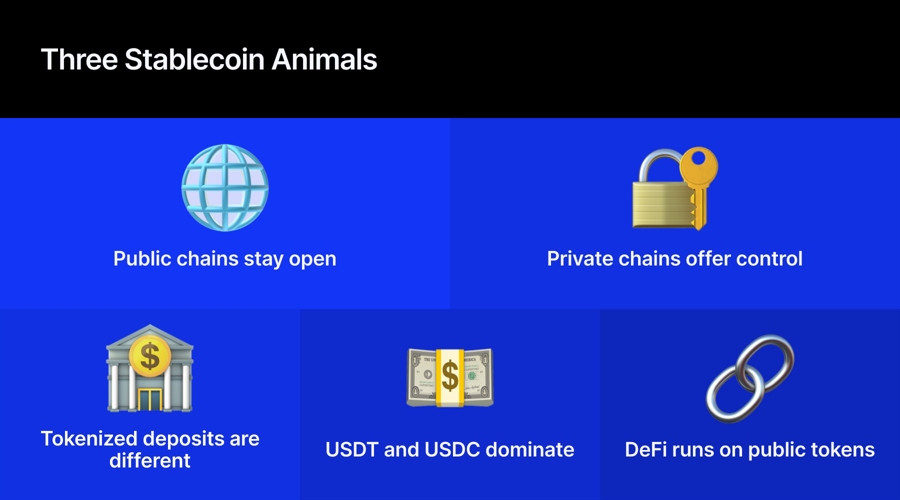
When you scroll through the financial news these days, you meet one stablecoin. The articles describe a digital dollar, a boring token that hugs the greenback, and a shiny new tool for Wall Street. Then you open a DeFi app and meet something else entirely, a lively instrument that moves at 3 a.m. on a Sunday and settles in seconds.
My complaint with the coverage is simple. The media keeps flattening three different animals into one word, and that word hides the parts I care about most. So let me separate the animals, because a public-chain stablecoin, a private-chain stablecoin, and a tokenized deposit do not share much beyond a family resemblance.
The Public-Chain Stablecoin
Start with the creature crypto natives know first. A typical stablecoin in our world is a fiat-collateralized token, and the idea is refreshingly simple. For every digital token an issuer mints on a blockchain, one real dollar sits in a bank account or in a short-term U.S. Treasury bill.
USDT and USDC dominate this market, and together with the rest of the field, they push the total stablecoin market cap past $300 billion in 2026. Traders use these tokens as the base pair for everything, parking value between bets without touching a bank. I use them for what I love most, which is DeFi.
They fuel lending markets on Aave, for instance, and they let anyone with a phone and a wallet earn, borrow, and settle without asking a branch manager for permission.
That permissionless quality is the whole point, and it is also the part the headlines skip. A public-chain stablecoin lives on Ethereum, Solana, or TRON and follows smart-contract code that anyone can read. You hold it in your own wallet with your own keys. You send a million dollars to a friend on another continent at 2 a.m. on a Sunday, and no bank approves the trip.
Every transaction is printed on a public ledger that anyone can audit with a block explorer. That transparency cuts both ways, and it is why regulators actually love these ledgers as tools for tracking illicit finance, but it also means the system answers to mathematics before it answers to a committee.
The Private-Chain Version
Now meet the second animal, the one Wall Street prefers. Banks can also mint dollar tokens, but they do it on private blockchains where only approved clients participate. JPMorgan runs JPM Coin on its own internal ledger, and the bank now moves billions of dollars a day for corporate clients through that system.
The industry calls this a wholesale stablecoin or a tokenized deposit, and the GENIUS Act, which President Trump signed in July 2025, explicitly lets licensed banks build on private chains with built-in controls. The differences from the public version are not cosmetic.
A corporation does not want rivals watching its treasury flows, a bank wants the power to freeze or reverse a mistaken transfer, and nobody wants to pay public gas fees that spike without warning. So the private chain trades openness for control, and it serves interbank settlements and large corporate payments rather than you and me.
The Third Animal Is Different
The third animal is not a stablecoin at all, even though journalists keep calling it one. The dollar balance you see in your PayPal or Venmo app is a stored-value liability under state money-transmitter law, and the balance in your Chase app is a commercial bank deposit insured by the FDIC up to $250,000.
The Federal Reserve's FedNow rail, which launched in 2023, settles bank dollars instantly around the clock without any ledger technology. Federal law draws a bright line here. To earn the name stablecoin, a digital dollar must exist as a token on a distributed ledger, and the law does not care whether that ledger is public or private.
Off-chain database dollars fall under older banking and electronic-money rules, and they come with fractional-reserve lending rather than the strict one-to-one reserve mandate that the GENIUS Act sets for payment stablecoins.
What Washington Sees
Notice what Washington sees in all of this, because the government views stablecoins through a completely different lens than either crypto natives or bankers do. Treasury officials cheer dollar-backed stablecoins as hungry buyers of short-term U.S. debt, and Tether alone holds roughly $140 billion in Treasuries, a stake that ranks it ahead of countries like South Korea and the United Arab Emirates.
Lawmakers wrote the GENIUS Act to turn stablecoin issuers into something like narrow banks that must hold cash and Treasuries one-to-one, publish audited reserve reports, and freeze tokens when law enforcement flags a wallet.
The law also strips stablecoins of any interest payment, and a separate executive order blocks the Federal Reserve from issuing a central bank digital currency. Washington therefore anoints the private, regulated stablecoin as America's digital dollar, treating the token more like a digital cashier's check than Bitcoin.
Why Reserve Quality Matters
That legal carve-out explains why the government refuses to call a payment stablecoin a security or a commodity. The SEC and the CFTC police bets on rising prices, and a token that stays at one dollar and pays no yield gives nobody an expectation of profit.
Banking regulators like the OCC and the Federal Reserve take the stablecoin file instead, because a run on a big issuer would spill into real banks and the Treasury market, while a crash in a speculative coin mostly burns its own holders. The 2022 collapse of TerraUSD perfectly illustrates risk.
That algorithmic coin had no real reserves backing it, and when trust evaporated, it fell from $1 to a few cents, wiping out about $45 billion in market value in days. Reserve quality is the entire game, and the law now writes that lesson into statute.
Where I Plant My Flag
Here is where I plant my flag. The private-chain version and the tokenized deposit do real work for corporate treasurers, and I welcome the clarity the GENIUS Act brings. I still root for the public one because openness compounds.
A permissionless dollar token lets a freelancer in Manila collect wages from Berlin in seconds for pennies, lets an unbanked teenager hold digital cash that no one can freeze with a phone call, and lets developers compose money into code the way they compose software.
DeFi turns those tokens into credit markets, savings tools, and insurance pools that run in the open, and every transaction leaves a public trail that any citizen can check. The private rails optimise for institutional comfort, while the public rails optimise for user dignity.
So the next time a headline calls stablecoins "boring digital dollars," ask which animal the writer actually means. The answer changes everything about the risk you hold, the rights you keep, and the future you get. I know which one I hold, and I know which one I cheer for.
This article was written by Anndy Lian at www.financemagnates.com.Why this matters
Federal Reserve is showing up inside the Stablecoins theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on Finance MagnatesRelated market context

As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.
As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield...
Coinbase Backs CFTC Prediction Market Push Amid Senate Backlash
Coinbase is urging the Commodity Futures Trading Commission to classify prediction market event contracts as swaps under federal l...
Crypto News Today: Bitcoin Price Nears $55K as Ethereum Plunges 10% and XRP Tests $0.87 Support
The November 21 selloff has kept all three cryptocurrencies under pressure, with moving averages indicating sustained bearish mome...
Strategy reports $35 billion net reserve with all Bitcoin unencumbered
Strategy's unencumbered Bitcoin and cash reserves enhance its financial stability, reducing risk during market downturns and prote...
Coinbase CEO Brian Armstrong says over 99% of customer crypto sits offline
Coinbase's robust offline storage strategy highlights the critical importance of security in maintaining trust and stability in th...

Coinbase Launches Crypto Options Globally, Bringing Deribit Liquidity to Retail Traders
Key Takeaways: Coinbase has rolled out cryptocurrency trading to qualified users outside of the United States. Contracts include B...