AI agents employ $24M market to act smarter as agentic crypto payments spread online
Lincoln Murr asked his AI agent to send some Twitter articles to his Kindle, copying a trick he'd seen suggested online. The agent scraped the articles with Firecrawl once Twitter started blocking it, then uploaded the r...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
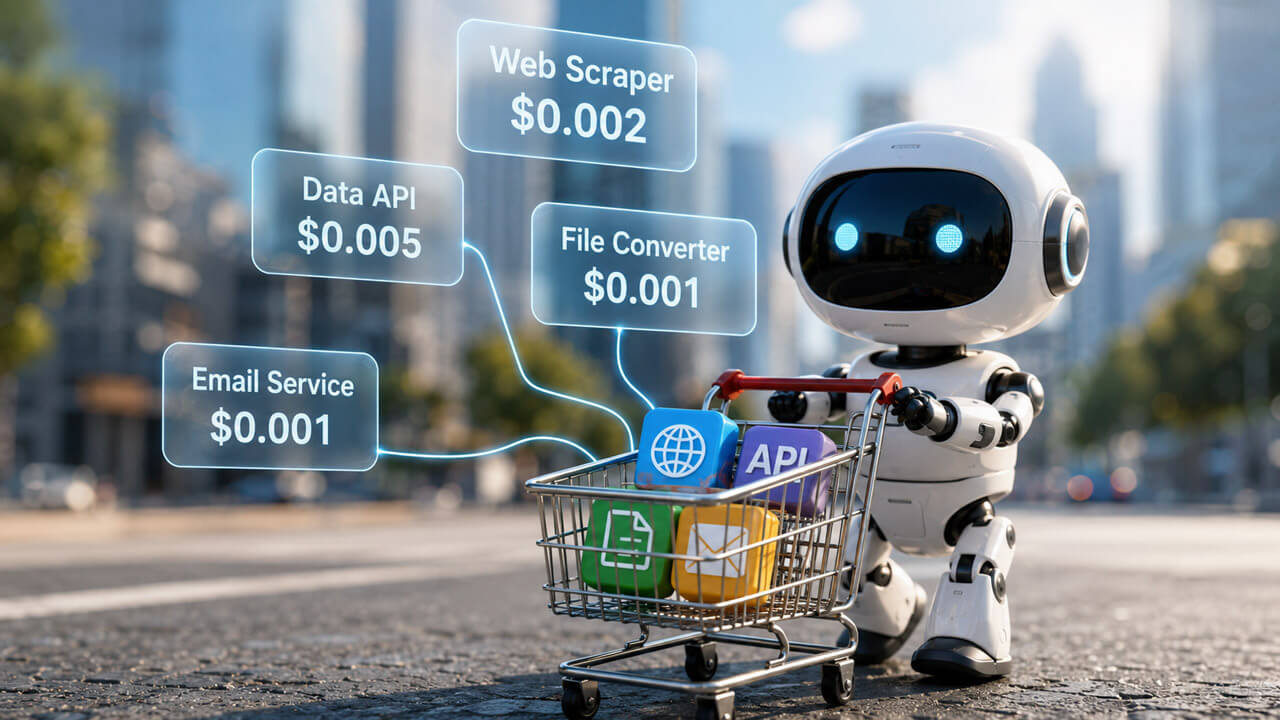
Lincoln Murr asked his AI agent to send some Twitter articles to his Kindle, copying a trick he'd seen suggested online. The agent scraped the articles with Firecrawl once Twitter started blocking it, then uploaded the result to a service called Stable Upload so it could reach his email.
Murr, who leads AI product work at Coinbase, told CryptoSlate he'd genuinely forgotten the agent even had a crypto wallet.
Both Firecrawl and Stable Upload sit among the expanding list of services built around x402, an open payment standard that lets software pay for access to the moment it needs it.
His agent picked both providers, paid them in small increments, and finished the task without a single approval from him along the way.
When the agent picks the vendorMost AI tools today work because a developer opened the account, generated the API key, and funded the credits.
Murr described a pattern taking hold in which an agent given a high-level task can shop for whatever capability it needs during the work itself.
He offered a cleaner example where a user asks an agent to turn a PDF into a podcast, and it can weigh Google's NotebookLM against ElevenLabs on cost, quality, and response time, then pick whichever fits the task, sometimes catching a first-time-user discount along the way.
Murr noted that the wallet does double duty, serving as both the agent's identifier and its payment method, a combination that replaces the whole ritual of signing up for API keys and pre-funding an account before an agent can touch a new service.
A flowchart contrasts developer-selected tool access, which requires pre-funded API keys, with agentic payments, in which agents discover, compare, and pay for tools at runtime.The Linux Foundation launched an x402 Foundation in April, with Coinbase contributing the original protocol alongside early backers including AWS, Stripe, Visa, Mastercard, American Express, Shopify, Google, Microsoft, and Cloudflare.
Coinbase's Bazaar now indexes over 10,000 paid tools that an agent can search and call directly, functioning close to Murr's description: a directory built with agents as the primary users.
AWS added a feature this June that lets CloudFront customers return a machine-readable price and payment terms to any bot requesting protected content, and then verify payment at the network edge before granting access.
Cloudflare launched its version in July, describing the new setup plainly: the agent becomes the buyer, and the request becomes the transaction.
From attention to utilityMurr framed the underlying move as a transition from an economy built on attention toward one built on utility.
He said that the internet runs a “Napster, Limewire” version of agent access, where an agent can scrape a site freely because there's no real equivalent of an ad for software to notice.
Cloudflare and AWS together sit in front of roughly half of global internet traffic, giving them the position to alter that by charging agents a few cents for the privilege of reading a page at all.
Murr argued that the same transition could hollow out the subscription model from underneath, as a flat monthly fee primarily benefits the business that collects it. A world where a million agents each pay a cent per call opens up something closer to walk-in retail: frictionless, one-off, and open to anyone.
He expects microtransactions to work as a top-of-funnel, with agents graduating into steadier vendor relationships, discounts, and bulk pricing once a pattern of paid use builds trust on both sides.
Who controls the directory?An economy where agents choose which services are paid raises the question of who ultimately decides what gets discovered and ranked.
Murr pointed to x402's governance as the answer, a foundation built from companies like Stripe and Coinbase that would ordinarily be competitors.
Cloudflare will still control what happens on sites that sit behind its infrastructure, and the broader goal is folding payment into the internet's plumbing itself, the way HTTP became a shared standard nobody owns.
x402 processed roughly 75 million payments totaling $24 million over a recent 30-day period, averaging about $0.32 per transaction.
However, a population-scale study published in July complicates the picture, finding that a large share of on-chain x402 settlement activity was either fictitious or occurred within linked internal clusters.
Genuinely independent economic activity falls somewhere in between.
The study could verify just $187,861 as payments to identifiable independent services. Another $20.07 million could be genuine, but the researchers could not rule out undiscovered links between the wallets involved.
Murr said that Coinbase wants to become what he called the backbone of the agentic economy, holding the accounts, the settlement rails, and the discovery layer all at once, and he pointed out that not enough people currently carry wallets that make these small purchases routine.
A chart compares x402's headline $24 million 30-day volume against a July study's estimated independent activity of $187,861 to $20.26 million. The test ahead for agentic spendingAgentic trading is the place to watch this get tested, since a trading agent's decisions produce a number you can grade directly against the cost of the data it bought.
Murr referenced a years-old idea from Ethereum's Vitalik Buterin that AI agents would end up as the primary traders in low-liquidity prediction markets precisely because their research cost is so low that it isn't worth a human's time.
Coinbase is building a product to let agents trade and pay directly from a retail account, and Murr expects the resulting loop, agents paying for premium data, using it to trade better, and pulling more data providers onto the rails, to gain real traction within six months.
If agents get reliably good at judging whether the next purchase is worth it, budget-aware routing becomes a genuine edge: comparing free and paid search, cheap and expensive models, raw and verified data, and, as one recent paper on budget-constrained reasoning found, smarter allocation beats brute-force approaches using four times the resources.
The strongest AI product in that world manages a portfolio of paid inputs, going well beyond simply running the largest available model.
Paid input What the agent must estimate When it is worth paying Failure mode Another search Whether new sources are likely to change the answer When confidence is low or the topic is fast-moving Paying repeatedly for duplicate information Premium data Whether proprietary data improves the decision enough to justify cost When the task has measurable financial or strategic value Buying “premium” data that adds no edge Stronger model Whether better reasoning is needed for this step When the task requires synthesis, judgment, or complex tradeoffs Using expensive models for simple tasks Verification Whether checking the result reduces meaningful risk When the cost of being wrong is high Underinvesting in checks to save pennies Specialist software Whether a purpose-built tool beats general reasoning When the task needs scraping, storage, formatting, trading, or execution Choosing cheap but unreliable toolsIf wallets, trust, and reliable value estimates remain scarce, the paid-access infrastructure keeps outpacing use, with most transactions confined to demos, internal testing, and narrow developer workflows, as the July settlement study already shows.
Murr's admission about weak demand becomes the more accurate read of where things stand: the rails exist well before the economy running on them does.
Every piece of that system, the wallet, the discovery layer, the settlement rail, exists to answer whether the next cent an agent spends will make its results better. Murr is chasing a real answer to that question alongside everyone else racing to build this economy, and right now that answer is still taking shape.
The post AI agents employ $24M market to act smarter as agentic crypto payments spread online appeared first on CryptoSlate.
Why this matters
Coinbase is showing up inside the AI Crypto theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context
Coinbase CEO Brian Armstrong says AI agents can give workers an unlimited team of L5-level staff
AI agents could revolutionize workforce dynamics, shifting focus from hiring to oversight, but human judgment remains crucial for...

As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.
As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield...
Coinbase Institutional: US dollar was the lone gainer as Bitcoin and Ethereum led monthly losses
Crypto market volatility highlights investor preference for stability, with institutions consolidating into perceived safer assets...

Hyperliquid Monero Crashes? Wagyu-Linked XMR1 Collapses, $13.2M Flows Into Ethereum
A Monero token crashed 99% on Friday after 5.2 million XMR1 tokens moved from a wallet tied to its creator, triggering a massive s...
Crypto News Today: Bitcoin Price Nears $55K as Ethereum Plunges 10% and XRP Tests $0.87 Support
The November 21 selloff has kept all three cryptocurrencies under pressure, with moving averages indicating sustained bearish mome...

Coinbase Launches Crypto Options Globally, Bringing Deribit Liquidity to Retail Traders
Key Takeaways: Coinbase has rolled out cryptocurrency trading to qualified users outside of the United States. Contracts include B...