Europe’s central banks want to scrap this stablecoin reserve safeguard
EU rules require stablecoins issued by electronic-money institutions to keep at least 30% of their reserves in commercial-bank deposits, rising to 60% for significant tokens. Britain's policy for systemic sterling stable...
Watchlist
Published in the last two hours. Multiple named entities are involved.
EU rules require stablecoins issued by electronic-money institutions to keep at least 30% of their reserves in commercial-bank deposits, rising to 60% for significant tokens. Britain's policy for systemic sterling stablecoin reserves excludes those deposits from coin backing. European central banks now want to remove the EU requirement, bringing the two approaches closer on the risk banks pose to stablecoin reserves.
Reuters reported on Sept. 22 that the European System of Central Banks, comprising the European Central Bank and EU national central banks, recommended replacing the compulsory bank-deposit share under the Markets in Crypto-Assets regulation with minimum reserve percentages in assets maturing within one and five working days. The proposal would change where issuers must keep redemption money; MiCA's existing requirements remain in force.
The same day marks the Bank of England's consultation deadline for its draft systemic stablecoin Code of Practice. Its June policy already ruled out commercial-bank backing because of financial, operational and contagion risks. The Bank intends to finalize the code by the end of 2026.
The regimes cover different types of issuer and are at different stages of implementation. Yet the recommendation points toward a shared concern: putting stablecoin reserves in banks can connect two sources of financial stress.
Related Reading Europe is actively trying to stop the dollar stablecoin takeover A stablecoin reserve can protect a coin and expose a bankMiCA's deposit requirements make commercial banks part of the mechanism for meeting redemptions. Cash that backs a token also becomes funding for the bank where the issuer holds it, tying the coin's ability to repay holders to that bank's ability to return the money.
The problem runs in both directions. In a June speech, the ECB explained that bank failure can damage confidence in the quality and availability of stablecoin reserves. USDC's March 2023 loss of its peg, when some backing sat at failing Silicon Valley Bank, illustrated that exposure.
Reverse the sequence and the risk moves into the banking system. If holders rush to redeem a stablecoin, the issuer may withdraw large deposits from its banks to repay them. Money held as a reserve for token holders becomes funding that a bank can lose abruptly.
The reserve can therefore transmit a run as well as help meet one. An issuer's attempt to honor its promise to token holders can force its banks to replace funding at precisely the moment confidence is weakening.
The recommendation reported by Reuters would focus requirements on short-maturity assets. Its proposed relaxation of a compulsory bank allocation differs from Britain's outright exclusion of commercial-bank backing.
The Bank of England's steady-state policy allows up to 70% in short-term UK government debt with no more than six months remaining to maturity, with 30% in central-bank deposits that pay no interest. Eligible issuers deemed systemic at launch can initially hold up to 95% in government debt as they scale.
Related Reading The UK softened stablecoin rules, but may still be capping its own marketCentral-bank deposits give the UK model a different source of redemption cash, alongside its securities holdings.
The regime primarily covers sterling stablecoins widely used in payments, jointly regulated by the Bank and Financial Conduct Authority after Treasury recognition. CryptoSlate covered the June policy when it was announced, ahead of the consultation ending today.
There is a reason to retain a substantial cash buffer. An ECB analysis of sovereign-bond markets argues that significant stablecoins issued by electronic-money institutions could meet redemptions equal to 60% of supply by drawing down deposits, without immediately selling sovereign bonds.
That benefit depends on the deposits being available. It nevertheless captures the trade-off: avoiding commercial-bank credit exposure can leave issuers needing to turn securities into cash when holders want repayment. Even short-dated securities can fluctuate in value or prove difficult to turn into cash under stress.
Related Reading Coinbase gives community banks a stablecoin bridge while supplying infrastructure underneathBritain's policy includes financial risk reserves and a planned central-bank liquidity backstop. Those protections address the difficulty of producing redemption cash under stress, when securities must be sold or financed to meet withdrawals.
For EU issuers, the next decisive step would be a change to MiCA's statutory floors. Removing the floors requires legislative amendment through the EU's lawmaking process. Until then, the deposit requirements remain the operating constraint.
For token holders, the comparison exposes what a stablecoin reserve percentage cannot answer by itself: whether the backing remains accessible, and how quickly it can become cash when redemptions accelerate.
The post Europe’s central banks want to scrap this stablecoin reserve safeguard appeared first on CryptoSlate.
Why this matters
USD Coin is showing up inside the Stablecoins theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context
EU central banks attack MiCA rules and stablecoin runs are blamed
Europe’s central banks want the European Union to rethink a rule designed to make stablecoins safer, but that can also link a toke...
ECB and EU Central Banks Want the Stablecoin Yield Ban to Reach Lending and Staking
The European Central Bank and the EU’s national central banks asked the European Commission to extend MiCA’s ban on paying interes...
Coinbase CEO Brian Armstrong Challenges Banks as Stablecoin Rewards Fight Grows
Coinbase CEO Brian Armstrong says USDC rewards should not be treated like bank-deposit interest, arguing that fully reserved stabl...
Coinbase users can now borrow USDC against bitcoin at a fixed rate
Coinbase now allows users to borrow the USDC stablecoin against their bitcoin at a fixed interest rate and repayment date.

Coinbase Prime opens institutional staking for TON, expanding its proof-of-stake lineup
Coinbase Prime's expansion into TON staking enhances institutional trust in blockchain investments, potentially boosting adoption...
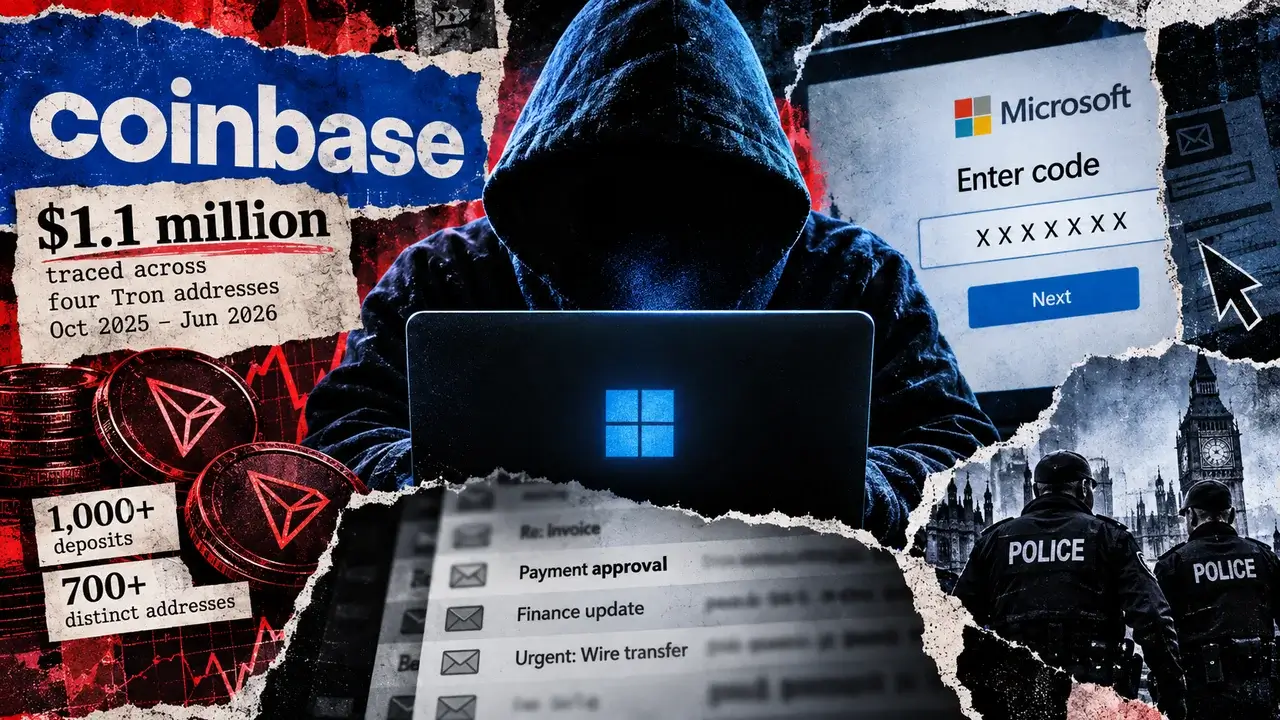
Coinbase traced $1.1 million crypto trail behind AI phishing service EvilTokens
Microsoft and Coinbase helped dismantle EvilTokens, an AI phishing service tied to more than 12,000 compromised inboxes worldwide....