Law Firm Fenwick Rejects Claims It Helped Enable FTX Collapse
Fenwick & West, a prominent Silicon Valley law firm, has rejected allegations that it played a central role in the collapse of crypto exchange FTX, calling the claims “facile” and “flawed” in a court filing on Monday. Ke...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
Fenwick & West, a prominent Silicon Valley law firm, has rejected allegations that it played a central role in the collapse of crypto exchange FTX, calling the claims “facile” and “flawed” in a court filing on Monday.
Key Takeaways:
- Fenwick & West has rejected claims it enabled FTX’s collapse, calling the allegations speculative and flawed.
- The firm argues it only provided routine legal services and had no knowledge of fraud.
- Fenwick says the amended lawsuit recycles claims already dismissed in similar cases, including those against Sullivan & Cromwell.
The legal pushback comes in response to an amended class-action lawsuit filed by FTX customers earlier this month in a Florida federal court.
Plaintiffs are seeking to update their 2023 suit, arguing that recent revelations from FTX’s bankruptcy proceedings and the criminal trial of founder Sam Bankman-Fried suggest Fenwick provided key legal support that enabled the fraud.
Fenwick Dismisses FTX Allegations as Speculative and MisleadingIn its filing, Fenwick dismissed the allegations as speculative and misleading, asserting it merely provided routine legal services typical of any outside counsel.
“Fenwick is not liable for aiding and abetting a fraud it knew nothing about,” the firm wrote, “based solely on allegations that Fenwick did what law firms do every day — provide routine and lawful legal services to their clients.”
The plaintiffs’ broader class-action case also includes claims against celebrities and companies linked to FTX.
While law firm Sullivan & Cromwell was initially named in the case, it was later dropped after a court-appointed examiner found no evidence the firm had knowledge of the fraud.
Fenwick said the latest complaint recycles similar accusations previously made against Sullivan & Cromwell, noting the plaintiffs “offer no credible reason why the same allegations should survive against Fenwick.”
Fenwick & West asked a Florida federal judge to shut down a bid by victims of the infamous FTX cryptocurrency scam to bring new claims against the firm, calling allegations that it knew about FTX's misuse of customer funds an "irresponsible falsehood." https://t.co/t9EIIyVHUG pic.twitter.com/51WZNGydli
— Law360 (@Law360) August 27, 2025Central to the new claims is testimony from Nishad Singh, FTX’s former lead engineer, who reportedly discussed Fenwick’s involvement in structuring loans.
Fenwick countered that Singh did not accuse the firm of helping cover up misuse of customer funds. Instead, the testimony described standard legal work on “founder loans,” which are common in startups.
Fenwick also argued that dozens of witnesses in Bankman-Fried’s criminal trial testified to being unaware of the fraud, including FTX’s internal lawyers, employees, and other external advisors, adding that “Fenwick is no different.”
Fenwick Rejects Claims It Promoted FTX’s FTT TokenThe firm further criticized new allegations that it helped launch and promote FTT, FTX’s exchange token, as violating Florida and California securities laws.
Fenwick labeled those claims “frivolous” and “untimely,” accusing plaintiffs of filing them only after a judge allowed state securities claims to proceed against celebrity endorsers.
“This is an eleventh-hour attempt to recast lawyers as ‘promoters,’” Fenwick said. “But this theory too goes nowhere.”
The court has yet to rule on whether the amended complaint will be accepted.
As reported, FTX has announced that it will begin its next round of cash distributions to creditors on or around September 30, 2025. The record date for eligible claimants was set for August 15.
The payments will be processed through FTX’s designated distribution partners, including BitGo, Kraken, and Payoneer.
Meanwhile, a Chinese creditor representing over 300 users is opposing FTX’s proposal to restrict payouts in 49 jurisdictions, including China, arguing it is legally unfounded and unfair.
The post Law Firm Fenwick Rejects Claims It Helped Enable FTX Collapse appeared first on Cryptonews.
Why this matters
This cryptocurrency story adds another data point to the current market tape and is useful when read alongside nearby source coverage.
Original source
Read on CryptonewsRelated market context
SEC Updates Crypto-Asset FAQs as Firms Seek Clarity on Federal Securities Rules
TL;DR: The SEC Division of Corporation Finance added questions 1.4, 1.5 and 1.6 to its crypto-assets FAQ on November 2, 2026. SEC...
Binance sits to benefit from First Digital listing
First Digital Trust, the firm behind the FDUSD stablecoin, announced early last month that it had signed a business combination ag...
North Korea denies involvement in $6.3B Binance hack, calls FBI claims absurd
Kim Yo Jong denies North Korea's role in the $6.3B Binance hack, calling FBI allegations absurd rhetoric as US authorities investi...
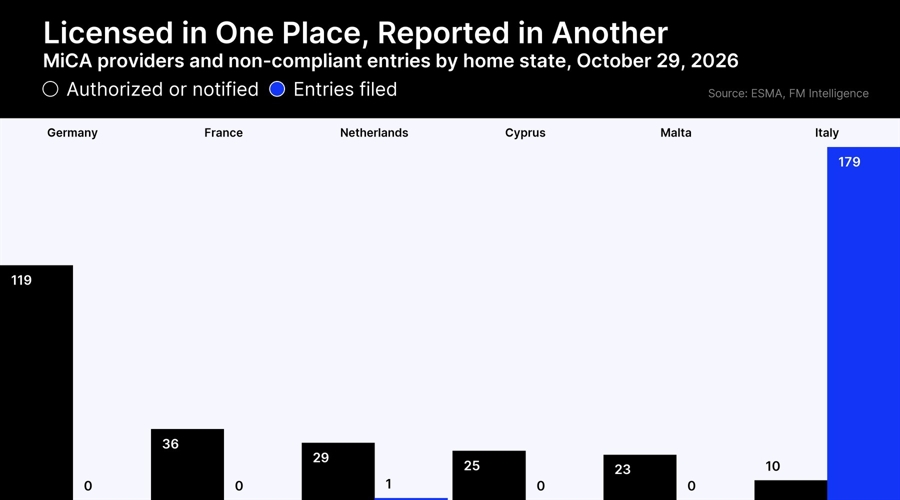
Italy Filed 95% of the EU's Register of Unlicensed Crypto Firms
Italy's market regulator filed 179 of the 188 entries on the EU's register of unlicensed crypto firms, an FM Intelligence analysis...
Democrats to Target Trump’s Crypto Ventures After Taking Congress
Bitcoin Magazine Democrats to Target Trump’s Crypto Ventures After Taking Congress House Democrats plan to open investigations int...
Bitcoin Price Prediction: Can BTC Reclaim $80K as US Midterm Election 2026 Fears Fade?
The US midterm election results initially triggered another wave of selling, but BTC quickly recovered as political uncertainty ea...