Why Europe is struggling to give Binance the MiCA license it needs
Binance withdrew its MiCA application in Greece after reported resistance and told users the absence of a formal decision before the transition deadline forced it to seek authorization elsewhere. Reports noted that talks...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
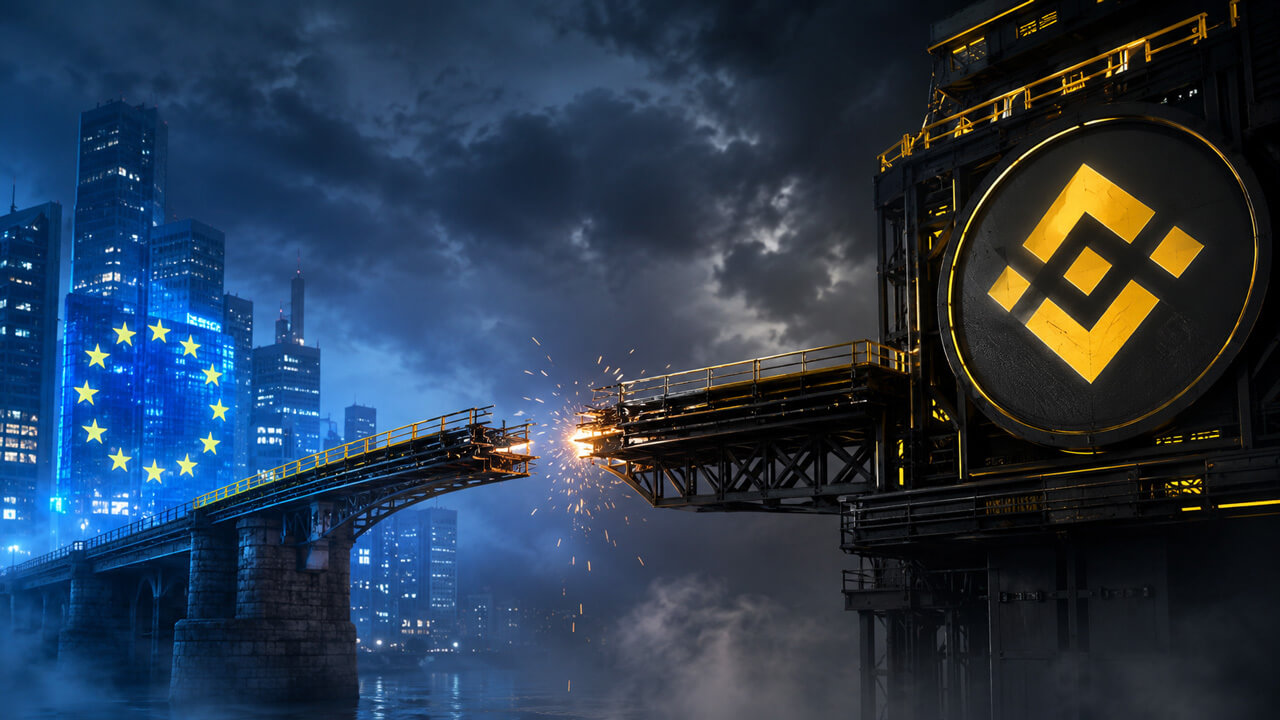
Binance withdrew its MiCA application in Greece after reported resistance and told users the absence of a formal decision before the transition deadline forced it to seek authorization elsewhere.
Reports noted that talks with regulators in Ireland and Latvia had also encountered friction, though Binance maintains that Greece was its only formal application.
ESMA has since directed unauthorized crypto-asset service providers to stop onboarding new EU clients and restrict existing services to exit and withdrawal activity.
A crypto-asset service provider license under MiCA is a fitness test administered by a national regulator, who, upon approving the applicant, extends that approval to all 27 EU Member States through passporting.
That regulator certifies Binance's management body, qualifying shareholders, AML controls, custody systems, client-asset segregation, internal governance, and group structure as sound enough to operate without borders.
Article 62 of MiCA spells out exactly what applicants must document. Article 63 gives national competent authorities explicit grounds to refuse authorization when the management body threatens sound and prudent management, client interests, or market integrity, or poses a serious risk of money laundering and terrorist financing.
Regulators can also consult AML authorities and financial intelligence units before granting any license. That architecture makes Binance's history the primary licensing evidence that regulators weigh before any authorization decision.
MiCA licensing area What the regulator must assess Why Binance is harder to approve Management body Good repute, competence, sound and prudent management CZ stepped down, but questions remain around influence and governance culture Qualifying shareholders Ownership, control, beneficial-owner risk Zhao remains a major beneficial owner AML/CFT controls Money-laundering and terrorist-financing risk DOJ, FinCEN, and OFAC settlements are directly relevant Custody and client assets Safeguarding, segregation, operational resilience A passported license would apply across the EU Group structure Clear legal entities and supervisory access Belgium previously flagged uncertainty around Binance entities Market integrity Systems to prevent abuse and protect clients Regulators must defend approval to the whole bloc A record that followsIn November 2023, the US Department of Justice announced that Binance pleaded guilty and agreed to pay more than $4 billion to resolve violations of the Bank Secrecy Act, money transmission, and sanctions, while Changpeng Zhao separately pleaded guilty to failing to maintain an effective AML program.
Treasury's FinCEN settlement reached $3.4 billion and OFAC's $968 million, both accompanied by monitorship and compliance undertakings.
A European regulator assessing Binance under MiCA must weigh that record as active evidence.
The DOJ and Treasury findings directly address the same controls that MiCA requires regulators to evaluate before authorizing passporting rights: AML systems, sanctions screening, management accountability, and group governance.
Binance argues that it has since rebuilt its compliance infrastructure, employing roughly 1,500 compliance staff and having no outstanding MiCA issues. The regulator's question is whether that rebuild is supported by evidence or merely asserted.
Europe's pre-MiCA history with Binance gave regulators in Greece, Ireland, and Latvia a file to consult as the company searched for an authorization route, and before any regulator had to make a bloc-wide licensing call.
Binance exited the Netherlands in 2023 after failing to register, following a fine from the Dutch central bank for operating without authorization. In Germany, the company withdrew its BaFin custody-license application after regulators reportedly made clear they would not grant it.
Belgium's FSMA ordered Binance to stop providing virtual-currency services from outside the European Economic Area, noting that Binance had not demonstrated which legal entities were offering services or whether they were properly authorized.
The FSMA also pointed to Binance's own terms, which referenced 27 corporate entities, 19 of them outside the EEA. French prosecutors opened a judicial probe in 2025 into allegations of money laundering and tax fraud, which Binance denied.
MiCA consolidates that accumulated record into a single authorization decision that cannot be reversed at the border.
A timeline of Binance's European regulatory setbacks from 2022 to 2026, spanning fines, market exits, and a withdrawn MiCA application. The CZ issueZhao stepped down as CEO in November 2023 as part of the DOJ settlement, but has remained a major beneficial owner, and Reuters reported that European regulators were examining his continued influence over the company.
Binance's EU regional head, Gillian Lynch, told Reuters that Zhao is fully removed from company management.
MiCA's fitness standards go beyond job titles: they require regulators to assess whether management and qualifying shareholders exercise effective control in a way consistent with sound governance, client protection, and market integrity.
A European authority approving Binance must document and supervise a group structure that proves the EU entity is insulated from informal control, reputational contagion, or group-level interference from outside the bloc.
MiCA's architecture places CASP authorization with the national competent authority, coordinated through AML/CFT consultation channels and ESMA guidance.
The ECB's explicit opinion role under the regulation applies to asset-referenced token issuers when monetary policy, payment systems, or financial stability are at stake, and it carries no equivalent lane for ordinary exchange authorization.
The ECB has separately advocated for stronger EU-level oversight of systemically important cross-border firms, an institutional reform position that addresses supervisory architecture.
France, Italy, and Austria have each warned that differences in national supervision could allow crypto firms to choose the regulator that imposes the lightest scrutiny.
French officials have explicitly described regulatory shopping as a search for the weakest link. A Greek, Irish, or Latvian regulator approving Binance would carry a bloc-wide political judgment, and would absorb reputational exposure if that decision later proved wrong.
Reports noted that regulators in Ireland, Latvia, and Greece coordinated closely, pointing to a collective supervisory posture.
Two futuresIf any EU Member State approves Binance after the company implements verifiable governance reforms, MiCA serves as a normalization path for large exchanges with compliance liabilities, granting Binance EU-wide access and regulators a documented framework that can withstand scrutiny in Paris and Rome.
If no regulator accepts that burden in the near term, the outcome will be a sustained period of restricted EU activity, with Binance users directed to sell or withdraw, while competitors with existing MiCA licenses absorb European market share.
Scenario What happens What regulators are signaling Market implication Normalization path Binance secures MiCA authorization in another EU Member State after verifiable governance and compliance reforms A national regulator is willing to certify that Binance’s controls, ownership, and governance are now defensible bloc-wide Binance preserves EU access; MiCA becomes a route for large exchanges to rehabilitate Gatekeeping path No regulator accepts the political and supervisory burden in the near term National authorities treat Binance’s past AML, governance, and group-structure issues as unresolved licensing evidence Binance faces restricted EU activity; licensed rivals absorb users and liquidityChainalysis estimated that illicit cryptocurrency addresses received at least $154 billion in 2025, with stablecoins accounting for 84% of illicit transaction volume. That backdrop gives regulators a stronger incentive to test major exchanges’ AML controls against evidence rather than assurances before granting passporting rights across the bloc.
The contest is over who bears the liability of the passport: Binance brings 300 million global users and more than 4 million EU app downloads last year, along with its compliance narrative, while EU regulators hold the authorization power and the reputational incentive to use it carefully.
MiCA's first major credibility test is whether any national authority deems Binance's evidence of change strong enough to stake the entire bloc's supervisory reputation on.
The post Why Europe is struggling to give Binance the MiCA license it needs appeared first on CryptoSlate.
Why this matters
Binance is showing up inside the Regulation theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context

As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.
As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield...
Binance.US derivatives bid clears CFTC completeness check, no approval yet
Binance.US's progress with CFTC could enhance regulatory compliance, but market impact remains limited without formal approval. Th...
NYSE taps Avalanche for tokenized securities, Bitwise cites privacy, security, and compliance
NYSE's adoption of Avalanche for tokenized securities highlights a shift towards blockchain solutions prioritizing privacy and com...
Binance hack: $2.82 billion frozen, only $32 million recovered
The Binance hack underscores the challenges of asset recovery in crypto, highlighting vulnerabilities in exchange security and leg...
Binance Hackers Move $860 Million in Ether as Bitcoin Laundering Surges
Hackers linked to North Korea have moved approximately $860 million in ether stolen from Binance over the past four days, while dr...
Binance raises RLUSD yield to 6.37% as XRP rewards surge 54%
At the base rate, a steady 10,000 RLUSD balance would have earned 12.72 XRP in the final week, while Binance’s notices leave buyin...