BlackRock’s staking Ethereum ETF pays yield but investors still prefer its $9 billion ETHA fund
Staking was supposed to strengthen Ethereum exchange-traded funds (ETFs), but BlackRock’s early results show investors still favor its original fund. When US spot Ethereum ETFs launched in July 2024, the absence of staki...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
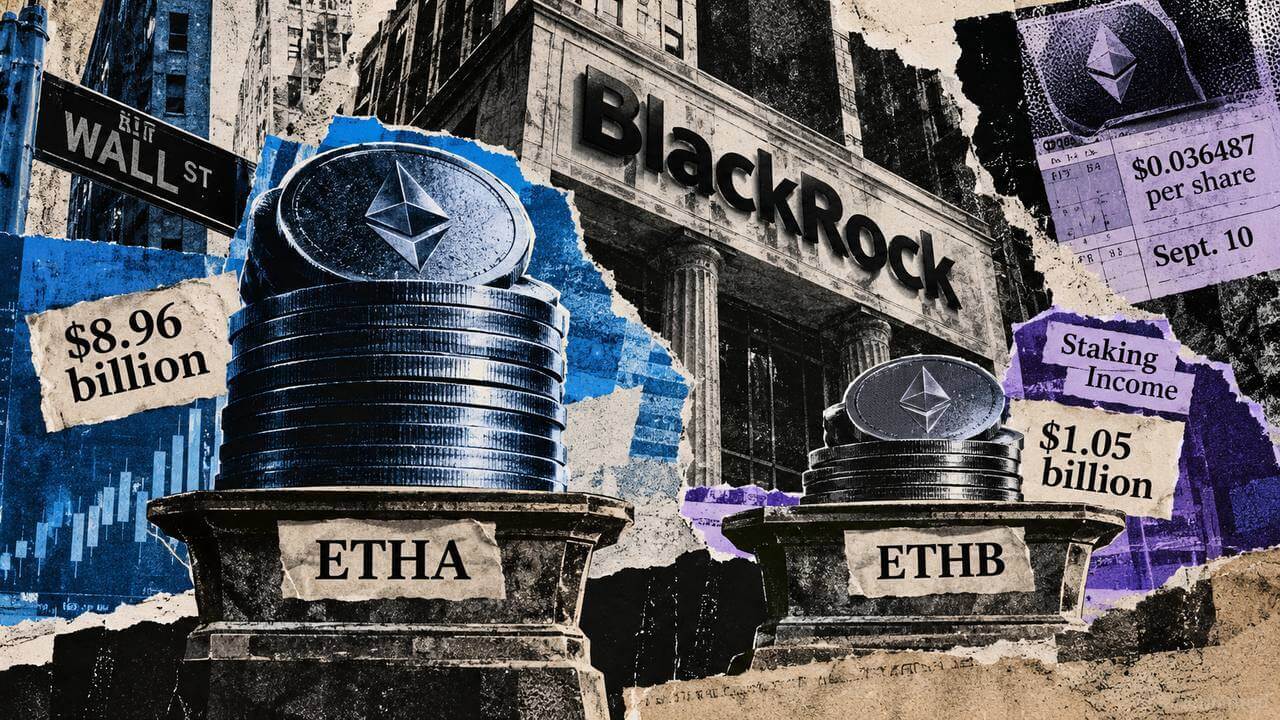
Staking was supposed to strengthen Ethereum exchange-traded funds (ETFs), but BlackRock’s early results show investors still favor its original fund.
When US spot Ethereum ETFs launched in July 2024, the absence of staking was widely identified as one of their biggest structural disadvantages. Investors buying the funds gained exposure to ETH's price but forfeited the rewards available to holders who committed their tokens to securing the Ethereum network.
At the time, JPMorgan cited the removal of staking from ETF filings as one reason it expected weaker demand than for Bitcoin funds. BitMEX Research similarly argued that institutional investors could find non-staking products less attractive, while Galaxy Digital estimated that giving up staking represented a meaningful opportunity cost for ETF investors.
BlackRock now offers an early test of that argument.
Its iShares Ethereum Trust ETF (ETHA) provides straightforward exposure to ether without staking. The newer iShares Staked Ethereum Trust ETF (ETHB) stakes part of its holdings and distributes a portion of the resulting income to shareholders.
So far, adding yield has not overturned the hierarchy.
ETHA held about $8.96 billion in net assets on Sept. 11, compared with roughly $1.05 billion for ETHB, BlackRock fund data show.
The difference is even larger in secondary-market trading: ETHA generated an estimated $1.86 billion of share turnover that day based on volume multiplied by its closing price, roughly 30 times ETHB’s $61.8 million.
ETHB is also paying investors. The fund listed a distribution of $0.036487 per share payable Sept. 10 after beginning to earn staking rewards in May.
Yet ETHA attracted $148.8 million of net inflows on Sept. 11, compared with $18.3 million for ETHB, Farside Investors data show.
The comparison comes with an important limitation. ETHA has had substantially more time to accumulate assets, trading relationships, and institutional adoption, while ETHB is still building its track record. Its roughly $1 billion asset base also represents meaningful demand for a newer product.
Related Reading Wall Street’s altcoin ETF rotation is not producing an altseason, and the old playbook may be breakingStill, ETHA’s continued inflows after staking income became available challenge the stronger version of the thesis that missing yield was the main constraint on Ethereum ETF demand.
Staking removes one handicap, but not ETHA’s head startETHB removes much of the opportunity-cost problem that shaped criticism of the original Ethereum ETF structure. It cannot immediately replicate the liquidity ETHA has accumulated since becoming one of the first US spot Ethereum ETFs.
BlackRock reported a 30-day median bid-ask spread of 0.05% for ETHA as of Sept. 11, compared with 0.06% for ETHB. That difference is small, but the much wider disparity in trading activity gives institutions substantially more capacity to enter and exit larger ETHA positions.
Daily flows have yet to show a sustained migration toward the staking product.
Both funds recorded no net flows on Sept. 8 and attracted capital on Sept. 9. ETHA suffered an outflow on Sept. 10 while ETHB gained assets, but both returned to inflows the next day, with ETHA attracting substantially more money.
Those movements cannot establish whether individual investors are rotating between the products. ETF flow data identify creations and redemptions at the fund level but do not reveal whether an investor selling ETHA subsequently used the proceeds to purchase ETHB.
That distinction matters if staking eventually changes the competitive balance. A sustained period of ETHB creations accompanied by ETHA redemptions would provide much stronger evidence that investors are actively exchanging simpler exposure for yield-bearing exposure.
Yield introduces costs and another layer of liquidity managementStaking also gives ETHB a more complicated economic structure than simply adding yield to ETHA.
About 75.85% of ETHB’s ether was classified as staked as of Sept. 10, while roughly 24.15% remained unstaked. The unstaked portion provides liquidity for fund operations and redemptions without requiring BlackRock to wait for ether to exit Ethereum’s staking process.
Investors also face two separate layers of charges.
ETHB carries a standard annual sponsor fee of 0.25%, the same headline rate as ETHA, although a temporary waiver reduces the fee to 0.12% on its first $2.5 billion of assets for 12 months beginning March 12.
Staking rewards carry another charge. An April prospectus supplement sets the aggregate staking fee at 10% of gross staking consideration, down from an earlier 18%.
The fees apply to different bases. The sponsor fee is assessed against fund assets, while the staking fee is deducted from rewards generated by participating in Ethereum’s proof-of-stake network.
Distributions are also conditional, not a fixed yield. BlackRock can consider staking consideration received, legal requirements, and the fund’s operational and liquidity needs when determining payments.
The structure introduces additional redemption considerations. Under stressed conditions, ETHB’s prospectus allows delayed settlement or cash-only redemptions when staking exit times or available liquidity make ordinary settlement more difficult.
Those trade-offs put the staking thesis to a tougher test than whether investors like receiving additional income.
ETHB must generate enough after-fee value to persuade investors to choose a younger, less-traded vehicle over an incumbent with nearly $9 billion in assets.
The next signal will be whether ETHB can convert its distribution feature into sustained creations rather than episodic demand around payouts. If that happens while ETHA begins losing assets, the staking thesis will have stronger support.
Until then, BlackRock can capture both preferences: investors prioritizing ETHA’s established liquidity and those willing to accept additional complexity to earn staking income through ETHB.
The post BlackRock’s staking Ethereum ETF pays yield but investors still prefer its $9 billion ETHA fund appeared first on CryptoSlate.
Why this matters
Ethereum is showing up inside the Ethereum ETF theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context

TOKEN2049 Singapore Schedule Puts Institutional DeFi on the 2026 Agenda
TOKEN2049 Singapore is scheduled for October 7–8, 2026, with confirmed speakers from Nasdaq, BlackRock, and Franklin Templeton app...
Ethereum bears keep selling but ETH price stays near $2,700 as US spot ETFs record $206M in outflows
Ethereum’s institutional demand is weakening around the same time derivatives positioning shows traders are selling aggressively w...
Circle, Ripple and Hedge Fund QRT Back Crypto Exchange OKX at $25 Billion Valuation
Stablecoin issuer Circle, Ripple, Standard Chartered’s investment arm SC Ventures and London-based hedge fund Qube Research & Tech...

Grayscale Ethereum Staking Mini ETF marks one year of staking payouts
Grayscale's staking ETF success may inspire broader adoption of yield-generating crypto products, attracting diverse investor inte...
Aave and Pendle may have found a way to keep yield capital from ever leaving DeFi
Aave is approaching a $67 million collateral rollover as one of its fastest-growing fixed-yield trades reaches maturity. About 67....
BlackRock Says AI Agents Could Be the Next Big Driver of Crypto Demand
Bitcoin Magazine BlackRock Says AI Agents Could Be the Next Big Driver of Crypto Demand Artificial intelligence and digital assets...