Ethereum’s post-quantum roadmap puts banks on a 2027 deadline nobody is talking about
Ethereum's post-quantum migration could create a problem for regulated banks years before any quantum computer poses a real threat to validator keys. Thomas Brunner, Sygnum Bank's Head of Custody and Staking, thinks diff...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
Ethereum's post-quantum migration could create a problem for regulated banks years before any quantum computer poses a real threat to validator keys.
Thomas Brunner, Sygnum Bank's Head of Custody and Staking, thinks differently about quantum risk in crypto than most people do.
Ethereum's Post-Quantum team says layer-1 upgrades could be completed by 2029, though it stresses there is no fixed date and the roadmap can still shift. The plan starts with a post-quantum validator-key registry before eventually replacing today's BLS validator signatures with hash-based alternatives such as leanXMSS.
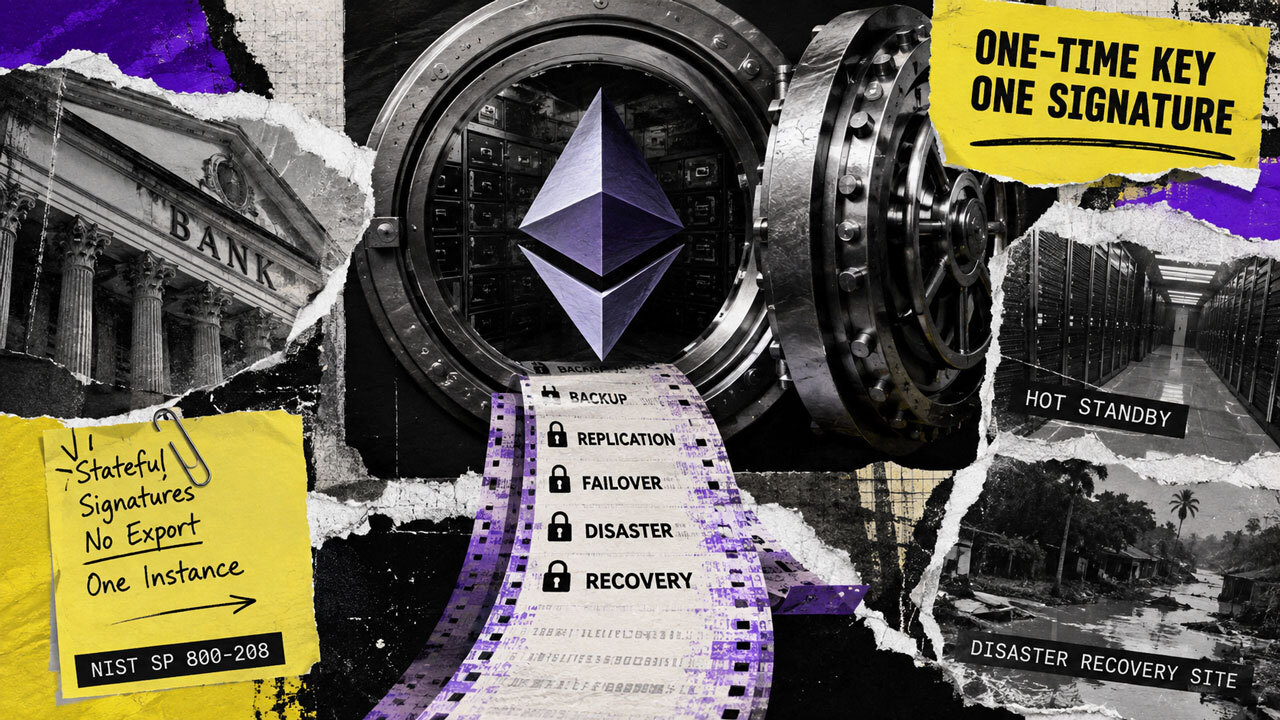
Ethereum shows why bank backups become the dangerBLS is the signature scheme that Ethereum validators use today, and it carries no state to manage, allowing a validator to sign as many times as needed. leanXMSS is built from a structure of one-time keys, and signing twice with the same index hands an attacker the material needed to forge a signature.
Related Reading Ethereum’s massive fee shock: New post-quantum signatures are 40x larger, threatening to crush network throughput and user costs Coinbase, Solana, Polkadot, and Bitcoin all moved on PQ planning, but wallet UX and aggregation may decide the winner. Jan 27, 2026 · Gino MatosNIST's SP 800-208 standard requires stateful hash-based signing to occur within a hardware module, bars the export of private key material, and expects the private key to exist in one instance.
Brunner said that the standard is blunt about the consequences and lacks a backup copy, which directly conflicts with how banks normally build resilience.
Backup, replication, hot standby, failover, and disaster recovery all either duplicate the signing environment or roll it backward in time. Restoring from an old snapshot reuses the index, and failing over to a standby that has been advancing its own counter does as well.
NIST is already working on a future revision that would allow controlled key export with mitigations, which would ease the non-export rule creating this conflict, but that update does not exist yet.
Bank resilience control Normal purpose XMSS/stateful-signature risk Backup Preserve recoverability if infrastructure fails Restoring an old copy can roll the signing index backward Replication Keep duplicate systems available across sites Two copies can diverge or reuse the same signing state Hot standby Allow rapid failover during outage Standby signer may not share the exact current key state Failover Move signing to another system after disruption A stale failover target can reuse one-time signing material Disaster recovery testing Prove the bank can recover critical systems Testing can accidentally create live duplicate signing states The multi-year runway banks needBrunner said a full cryptographic inventory, mapping every place a key lives and what depends on it, typically takes six months to a year on its own, before a bank touches anything.
Banks sign inside hardware security modules, and Brunner said the bank cannot move faster than its vendors ship and certify post-quantum support with reliable state handling, a validation cycle it does not control.
Key ceremonies and dual-control procedures then need to be redesigned, followed by internal risk approval, external audit and, where relevant, supervisory review. Put those steps in series, and the arithmetic alone produces a multi-year timeline.
A bank beginning its inventory in 2027 would be roughly on time for a 2029 target.
Migration step Why it matters Timing pressure Cryptographic inventory Map every key, dependency, vendor, and control path 6–12 months before changes begin HSM/vendor readiness Banks depend on certified signing hardware and state handling Outside the bank’s direct control Key ceremony redesign Existing dual-control and recovery procedures may not fit XMSS Requires operational rewrite Risk approval Internal control owners must approve the new model Adds governance lead time External audit Auditors must retest the custody-control description Cannot happen at the last minute Supervisory review Regulators may need to understand the changed custody process Adds uncertainty before launch Regulators are already flagging the planning gapSwitzerland's FINMA surveyed 60 financial institutions on quantum computing risk between November 2025 and January 2026 and found most understood the danger but lacked a clear migration roadmap.
The regulator's July report found that 72% of institutions had neither planned nor implemented measures for quantum-safe encryption, and only 8% had a specific roadmap.
FINMA's findings describe a broader planning gap across traditional finance, one Brunner said is the cheapest part of the problem to close because a roadmap alone would fix it.
Ethereum's proposed validator-key registry would cap the number of post-quantum keys the network processes per slot, with researchers currently using 16 registrations per slot as a representative parameter to spread the transition over weeks or months.
Ethereum Research has warned that a last-minute rush to register could overload the queue and leave validators unable to sign once BLS is deprecated, threatening finality itself.
Brunner's point about the queue is that a bank arriving late registers alongside every other latecomer and cannot control where it lands in line. Being early is the only way a bank can gain any real influence over its place in that queue.
What breaks firstBrunner's sequence for how a bank runs into trouble starts with the audit itself. If the signature scheme underneath a bank's custody process moves to something new but its documented controls have not been redesigned and retested, the attestation no longer describes what the bank is doing. Auditors rely on that description holding.
A validator that cannot produce signatures accepted under the prevailing consensus rules stops performing its duties, and any resulting penalties are borne directly by client positions.
Brunner said a bank that cannot describe and evidence a compliant custody process should not keep onboarding client assets into it. Cryptographic compromise, the scenario most people picture first, arrives last in his sequence.
Failure stage What happens Why it matters 1. Audit/attestation breaks Documented controls no longer match how keys are actually handled The bank can no longer evidence control of client assets 2. Validator operations degrade Validators fail to produce accepted signatures Staking performance and penalties affect client positions 3. New onboarding slows or stops The bank cannot evidence a compliant custody process Business impact arrives before cryptographic compromise 4. Cryptographic compromise Quantum or state-reuse attack becomes practical This is the last risk in Brunner’s sequence, not the first Ethereum can show how the transition could go from hereThe bull case has hardware vendors shipping state-aware signing modules in time, with monotonic counters and atomic state updates giving auditors a clean pattern to test against.
NIST's anticipated revision to its export rules gives banks a safer way to build redundancy without duplicating usable key material, and Ethereum's registry incentives keep registration spread out as intended. Banks that started their inventories in 2027 clear internal and external review with room to spare.
The bear case has a bank starting its inventory in 2028 or later, discovering validator keys embedded across vendor stacks, staking providers, and disaster-recovery procedures it cannot fully map in time.
Auditors issue a qualified finding once they realize that the documented controls no longer align with how keys are handled, and that new staked-ETH onboarding slows or stops. The bank still has to join Ethereum's registration queue behind everyone else who waited too.
Reaching an ordinary audit day without being able to prove control of validator keys is enough to fail Ethereum's quantum transition, with or without a working quantum computer anywhere in sight.
The post Ethereum’s post-quantum roadmap puts banks on a 2027 deadline nobody is talking about appeared first on CryptoSlate.
Why this matters
Ethereum is showing up inside the Security Incidents theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context

As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.
As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield...

Coinbase Launches Crypto Options Globally, Bringing Deribit Liquidity to Retail Traders
Key Takeaways: Coinbase has rolled out cryptocurrency trading to qualified users outside of the United States. Contracts include B...
Behind Closed Doors, Central Banks Build a Case for Bitcoin—But With Gold
In conversations behind closed doors, central bank officials explain that these institutions hold gold and don’t want tokenized go...
Coinbase moves 127,745,921 USDC from institutional arm to its exchange
Coinbase's internal USDC transfers highlight the growing importance of stablecoins in liquidity management and operational efficie...

Tether Backs SCRYPT to Scale Institutional Stablecoin Payments Across Global Markets
Key Takeaways: Tether has staked money in the Swiss stablecoin platform called SCRYPT. This deal is meant for institutional paymen...

Elon Musk’s Grok AI Predicts ETH Vs SOL For 2027: Who Wins?
Ethereum vs. Solana in 2027: Elon Musk’s Grok AI predicts which is positioned for bigger gains at the end of this article. As of m...