Standard Chartered says Ethena’s ENA could crush Bitcoin and Ethereum returns by 2028
Standard Chartered expects Ethena’s ENA token to rise about sevenfold by 2028, provided the protocol can rebuild its shrinking synthetic-dollar business. The bank initiated coverage of ENA with a $2 year-end 2028 target,...
Watchlist
Published in the last two hours. Multiple named entities are involved.
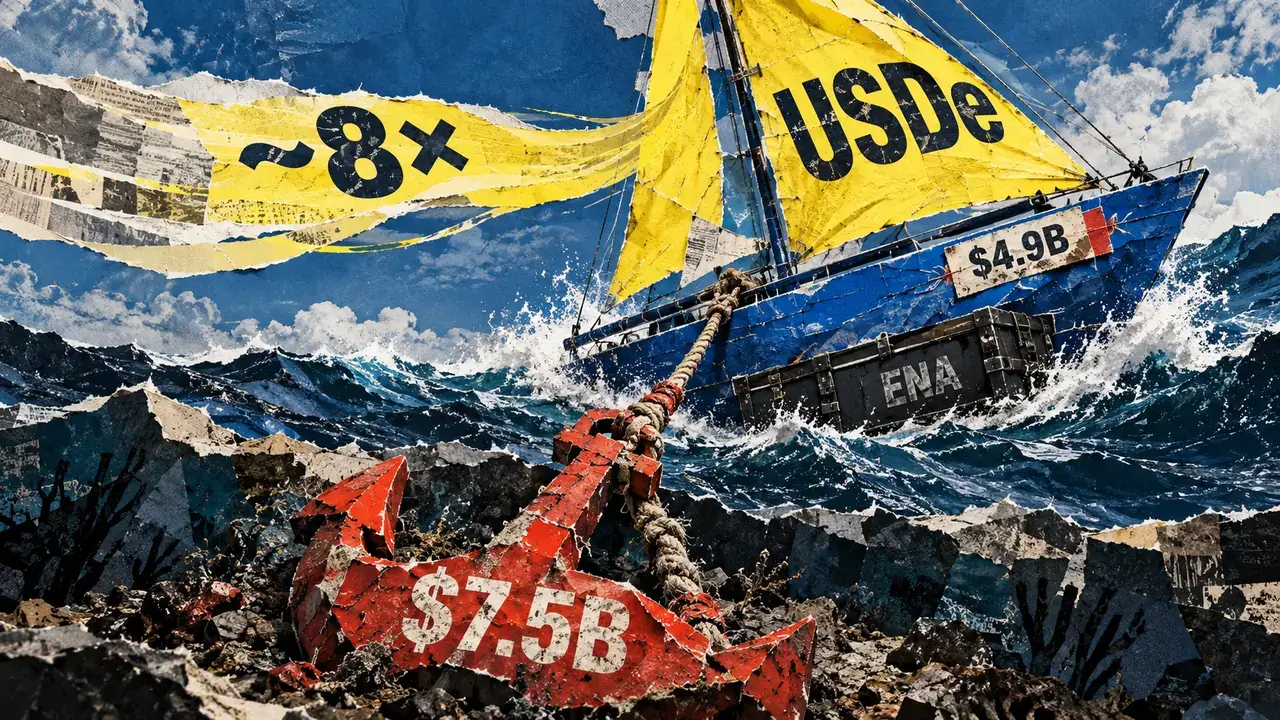
Standard Chartered expects Ethena’s ENA token to rise about sevenfold by 2028, provided the protocol can rebuild its shrinking synthetic-dollar business.
The bank initiated coverage of ENA with a $2 year-end 2028 target, up from about $0.28 currently. It forecasts the token reaching $0.42 at the end of 2026 and $1.10 in 2027 before accelerating further the following year.
The projection would leave ENA outperforming Standard Chartered’s expected gains for both Bitcoin and Ethereum over the same period. But reaching it requires Ethena to reverse a contraction that has cut USDe supply by more than half from its peak and expand far beyond the scale it has previously achieved.
Standard Chartered's Projected Returns For Ethena, Ethereum and Bitcoin by 2028 (Source: Standard Chartered)The bank’s thesis rests on Ethena finding new sources of yield as returns from its original crypto trading strategy decline, while generating enough revenue from a much larger USDe base to make ENA increasingly valuable to holders.
Ethena first has to rebuild USDeUSDe became one of crypto’s fastest-growing stablecoins after launching in late 2023, exceeding $10 billion as traders piled into a structure that combined long spot crypto positions with short perpetual futures.
That approach allowed Ethena to capture funding payments while keeping its overall market exposure largely delta-neutral. At times, the strategy generated returns above 20%, helping attract deposits into USDe and its yield-bearing counterpart, sUSDe.
However, those conditions have since weakened amid the ensuing market contraction.
As the trade became more crowded and crypto funding rates compressed, USDe supply fell to about $4.9 billion. Standard Chartered estimates Ethena’s blended yield across its strategies is now about 5.2%.
The bank’s forecast assumes contraction can reverse dramatically. It expects USDe supply to reach $40 billion by 2028, meaning Ethena would first have to regain its previous $10 billion-plus peak and then roughly quadruple again.
Ethena has responded to lower crypto basis returns by broadening where it generates yield. Its strategies now include DeFi lending, institutional lending, liquid stablecoins and real-world assets, alongside newer basis trades tied to equities and commodities.
Related Reading Ethena is targeting the $120 trillion Wall Street stock market to hunt yields 5x higher than BitcoinThat diversification is central to Standard Chartered’s growth assumptions.
The bank expects tokenized assets, including stablecoins and other real-world assets, to reach about $4 trillion by the end of 2028 from roughly $350 billion currently. It projects real-world assets deployed on blockchains could rise from about $40 billion to $2 trillion over the same period.
A larger tokenized-asset market would give Ethena more collateral and yield opportunities beyond crypto derivatives, potentially allowing USDe to expand without requiring another period of exceptionally high perpetual-futures funding rates.
Ethena is also building businesses outside the core synthetic dollar, including white-label stablecoins and Ethena Pay. Standard Chartered expects those operations to widen the revenue base as the protocol grows.
However, the first hurdle is much closer than $40 billion.
Ethena’s approved fee-switch framework begins at $7.5 billion of USDe supply, leaving the protocol below the first threshold at which the revenue mechanism underlying Standard Chartered’s valuation begins to take effect.
Why the buyback math leads to $2Once those thresholds are crossed, the ENA valuation increasingly depends on how much of Ethena’s economics can be directed toward token holders.
The approved framework allocates 95% of qualifying net revenue paid to the Ethena Foundation from covered businesses toward ENA buybacks. Ethena does not retain the full yield generated by the assets supporting USDe, making the distinction between gross and net revenue central to the calculation.
Blockworks Advisory’s analysis modeled the protocol’s share of gross revenue increasing with USDe supply, beginning at about 5% around $7.5 billion and reaching 20% by $20 billion. The model used a 6% protocol yield as an illustrative assumption, not a guaranteed return.
At the much larger scale envisioned by Standard Chartered, those economics become substantial.
The bank estimates that if USDe reaches $40 billion, ENA purchases could amount to roughly 23% of the token’s current market value annually if its price remained unchanged.
Standard Chartered does not expect such a percentage to persist. It argues that investors would capitalize the expected stream of purchases into ENA’s valuation, pushing the token higher and reducing annual buybacks as a percentage of its market capitalization.
The bank points to Uniswap as an analog, saying UNI’s annualized buyback percentage has settled around 3% to 4% as the token appreciated after activating its fee switch. Applying a comparable equilibrium to Ethena underpins Standard Chartered’s $2 target.
But the mechanism introduces its own constraint.
Capturing a larger share of Ethena’s revenue for the protocol can reduce what remains available to sUSDe holders. That creates a balancing act: Ethena needs enough margin to support ENA purchases while maintaining sufficiently competitive yields to keep attracting the deposits required for USDe to grow.
The assumptions become more demanding as supply rises. The 6% return used in the framework has not been guaranteed across market cycles, while the higher revenue-capture tiers have yet to be tested at the scale Standard Chartered expects.
That leaves investors with several nearer-term checkpoints before the $2 target becomes relevant. USDe must first cross the $7.5 billion fee-switch threshold and reclaim its previous peak.
Beyond that, Ethena will have to show that its newer yield strategies can absorb tens of billions of dollars without materially compressing returns. How quickly those thresholds are crossed will determine whether Standard Chartered’s projected buyback engine begins to resemble the one embedded in its valuation model.
The post Standard Chartered says Ethena’s ENA could crush Bitcoin and Ethereum returns by 2028 appeared first on CryptoSlate.
Why this matters
Bitcoin is showing up inside the Stablecoins theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context
Standard Chartered initiates Ethena coverage, sees ENA at $2 by 2028
Ethena's growth in tokenized assets and stablecoins could significantly impact DeFi and traditional finance by 2028, despite poten...
Morgan Stanley Sets Up Lab to Test Stablecoins and DeFi
Morgan Stanley has established an internal Digital Asset Lab to test stablecoins, tokenization and decentralized finance applicati...

XRP News: Brazil $4T Financial Infrastructure Expands Onto XRPL
CSD BR, a Brazilian financial-market infrastructure operator overseeing more than 22 trillion reais in registered assets, has been...
Kalshi’s $40 billion growth story hits tough questions about its trading volume
Kalshi is ending a trader-volume incentive program nearly a year early as scrutiny of activity in its crypto markets intensifies....
Bitcoin Price Prediction: Is the BTC Correction Over as It Defies September’s Red Trend?
Bitcoin price is near $83,100, a stable 24-hour movement after retreating from $87,400, and with its prediction still leaning bull...
Open USD Stablecoin Goes Live as Stripe, Visa and Mastercard Open It to Businesses
Open USD (OUSD), the dollar stablecoin backed by Coinbase, Mastercard, Shopify, Stripe and Visa, went live on Wednesday, its opera...