Why Bitcoin bulls shouldn’t mistake a shrinking dollar reserve share for central bank buying
A Sept. 2, 2026 analysis by New York Fed researchers shows how a few large reserve portfolios can lower the global dollar share without a broad retreat from dollars. For investors assessing future sovereign demand for Bi...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
A Sept. 2, 2026 analysis by New York Fed researchers shows how a few large reserve portfolios can lower the global dollar share without a broad retreat from dollars. For investors assessing future sovereign demand for Bitcoin, the distinction is between a changing average and an investment decision.
Linda S. Goldberg, Oliver Hannaoui and Sneha Parthasarathy report that the dollar share of global official foreign-exchange reserves fell from 64% at year-end 2015 to 56% at year-end 2025, using IMF COFER data.
Their country-level evidence points to concentrated decisions and changes in reserve sizes.
Countries can change the currency mix of their portfolios, the “preferences” channel. Alternatively, their total reserves can grow or shrink, changing their weight in the global average.
When a country with a below-average dollar allocation accumulates reserves, it can pull down the worldwide dollar share without cutting its own allocation. Switzerland did that between 2015 and 2019: its reserve growth pushed the aggregate share down even as its own dollar allocation rose.
For that period, 76 countries had complete endpoint data within a 79-country exercise. Their preferences and reserve-size contributions declined by 1.2 and 1.5 percentage points, respectively.
For 2019-2023, the 62 countries with complete data contributed a positive 0.3 percentage point through preferences and a negative 0.5 percentage point through reserve-size changes.
China, Russia, Mexico and Morocco lacked 2023 dollar-allocation data. Under assumptions matching the observed 2.3-percentage-point global decline, the researchers inferred a combined negative 2.0-percentage-point preferences contribution for that group.
Infographic shows 2023 dollar-reserve data missing four countries and explains that reserve-share statistics do not establish sovereign Bitcoin purchases. A Bitcoin allocation needs its own evidenceThe underlying Staff Report 1087, issued in March 2024 and revised in February 2026, separates reserves needed for liquidity from an investment portion above those needs. Trade payments, foreign-currency debt, and currency stabilization sustain the need for liquid reserves.
The paper models that investment portion using short-term external debt or three months of imports as alternative measures of liquidity needs.
Diversification is more prevalent when reserves can satisfy those needs. Its earlier decomposition covers 2015-2020, while its broader country panel spans 1999–2023.
Related Reading Arthur Hayes calls EUR/JPY prices crypto’s smoke alarm, but the Fed’s plumbing still shows no fireThe distinction also applies when a central bank actually buys Bitcoin. On Nov. 13, 2025, the Czech National Bank announced a $1 million digital-asset test portfolio including Bitcoin, with a dollar stablecoin and tokenized deposit also part of the project.
The amount covered the whole portfolio, and the purchase was explicitly outside international reserves.
Applied to Bitcoin, the reserve research supports a limited inference: diversification beyond liquidity needs does not identify the money's destination. Neither New York Fed source measures sovereign Bitcoin purchases or estimates a Bitcoin price effect.
A sovereign Bitcoin demand case needs separate evidence: a disclosed allocation, its funding source, and executed purchases, with official reserves distinguished from holdings outside them. A shrinking dollar share supplies none of those details.
The post Why Bitcoin bulls shouldn’t mistake a shrinking dollar reserve share for central bank buying appeared first on CryptoSlate.
Why this matters
Bitcoin is showing up inside the Institutional Adoption theme, so this story is worth tracking for follow-through rather than treating it as a one-off headline.
Original source
Read on CryptoSlateRelated market context
Circle and Tether find common ground against MiCA’s bank reserve rules
Circle is urging the European Union to open its Markets in Crypto-Assets Regulation (MiCA) to foreign-regulated stablecoins and lo...
New Treasury rules could change how stablecoin issuers get your dollars back
US government debt is one of the easiest assets in the world to borrow against, which lets financial companies get cash without gi...
Bankers sue to overturn OCC trust-bank rule used by crypto firms
The Independent Community Bankers of America sued the OCC in federal court in Washington on Oct. 2, two weeks after the agency app...
Kraken operator Payward and Singapore Gulf Bank platform for 24/7 institutional crypto settlement
The two firms will initially roll out the digital assets settlement service to select institutional clients in Asia and the Gulf r...

American Bankers Sue OCC Over Crypto Bank Charters, Challenging Coinbase and Circle
The lawsuit, filed October 2 in the U.S. District Court for the District of Columbia, puts the growing role of crypto firms within...
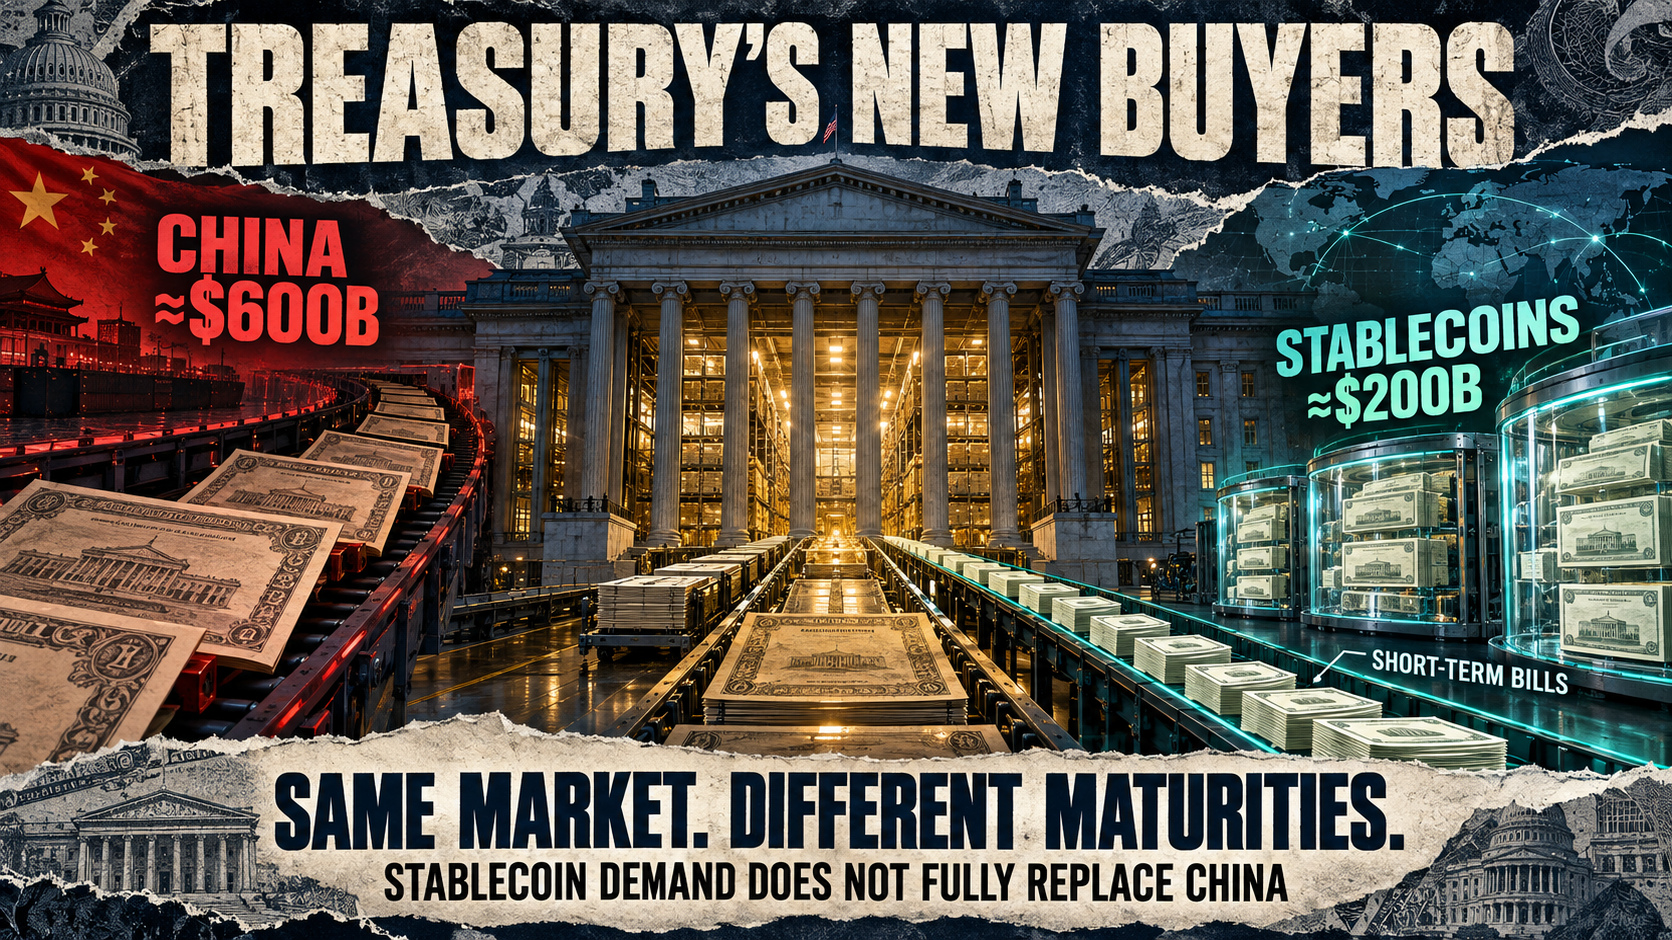
Stablecoin issuers have replaced 40% of China’s lost US Treasury demand
Stablecoin issuers are emerging as a new source of demand for US government debt as foreign official holdings lose ground. Tether...