Visa and Bridge Partner to Make Stablecoins Accessible for Everyday Purchases
Key Takeaways: Visa and Bridge enable seamless stablecoin-backed Visa cards through a single API integration Initial rollout in six Latin American countries, with Europe, Africa and Asia slated for late 2025 Users transa...
Archive context
Older archive item. Useful for background and entity history, but not a fresh market-moving signal.
Key Takeaways:
- Visa and Bridge enable seamless stablecoin-backed Visa cards through a single API integration
- Initial rollout in six Latin American countries, with Europe, Africa and Asia slated for late 2025
- Users transact USDC, USDP and other stablecoins at 150 million+ Visa merchant locations worldwide
- Bridge handles on-chain deduction, fiat conversion, settlement and compliance alongside Lead Bank
- Developers gain programmable controls over fees, spending limits and governance via Bridge’s dashboard
Visa and Bridge have joined forces to transform dollar-pegged stablecoins from niche trading assets into everyday payment instruments. Rather than requiring merchants to adopt specialized crypto infrastructure, the partnership embeds stablecoin functionality within Visa’s existing payment rails. Consumers load their stablecoin balances—USDC, USDP or other approved tokens—into a Bridge-enabled wallet or app, then use a Bridge-issued Visa card to pay. When a transaction is initiated, Bridge deducts the exact stablecoin amount from the user’s on-chain balance, converts it instantly into the merchant’s local fiat currency, and settles the payment over Visa’s global network in real time.
How It Works Under the HoodBridge provides a unified API and backend layer that abstracts blockchain intricacies:
- One-Time Integration: Developers connect once to Bridge and can issue stablecoin-backed Visa cards across multiple countries without further API work.
- Instant Conversion: Bridge continuously monitors on-chain balances and triggers swaps—either via smart contracts or off-chain liquidity providers—to fund each purchase, then hands off settlement to Visa’s authorization and clearing network.
- Universal Acceptance: The resulting Visa card functions identically to any other Visa product, accepted at over 150 million merchant locations worldwide—both in-store (contactless, chip and PIN) and online.
Bridge maintains fiat liquidity pools and partners with leading market makers to ensure conversions occur at minimal slippage. Merchants experience standard Visa settlement, seeing no difference in timing, fees or reporting compared to conventional card transactions.
Developer AdvantagesBridge’s platform accelerates stablecoin card deployment and scaling:
- Geo-Agnostic Rollout: Start immediately in Argentina, Colombia, Ecuador, Mexico, Peru and Chile; expand to Europe, Africa and Asia by late 2025.
- Programmable Controls: Through Bridge’s dashboard or API, developers can configure dynamic fee schedules, per-card and per-user spending caps, whitelisting rules and split-settlement logic for revenue sharing.
- Compliance as a Service: By sponsoring cards through Lead Bank, Bridge centralizes KYC/AML, transaction monitoring and regulatory reporting—obviating the need for each fintech to secure individual banking relationships or build compliance stacks.
This “build once, deploy everywhere” model empowers both startups and incumbents to focus on user experience, loyalty programs and market growth rather than piecing together fragmented payment infrastructure.
Consumer ExperienceFrom the cardholder’s perspective, payments feel entirely familiar:
- Instant Checkout: No manual on-ramp, fiat conversion or exchange login—spend directly from stablecoin balances.
- Digital Wallet Integration: Bridge-issued cards add seamlessly to Apple Pay, Google Pay, Samsung Pay and other digital wallet platforms for contactless convenience.
- Self-Custody Until Spend: Users retain control of funds on-chain until the moment of purchase, reducing reliance on centralized custodians and associated counterparty risks.
- On-Chain Audit Trail: Every transaction generates an immutable blockchain record, offering unmatched transparency and simplifying reconciliation.
Some pilot programs layer in tokenized loyalty rewards—crypto-back rebates or points redeemable for NFTs—merging DeFi incentives with everyday spending habits to boost engagement.
Focus on Latin America, with Global AmbitionsLatin America’s high remittance costs, inflationary pressures and underbanked populations make it an ideal proving ground:
- Expensive Remittance Corridor Fees: Traditional cross-border transfers often charge over 5% in fees; stablecoin rails can reduce that by up to 70%.
- Mobile-First Demographic: Many Latin American users rely on smartphones as their primary financial interface, making digital wallets and crypto apps a natural fit.
- Hedge Against Local Currency Volatility: Stablecoins offer a refuge for residents in countries experiencing rapid currency depreciation, like Argentina and Venezuela.
By demonstrating clear value in these markets, Visa and Bridge refine compliance workflows, liquidity provisioning and user interfaces. Subsequent expansions into Europe, Asia and Africa will adapt learnings—such as multi-jurisdiction licensing and FX routing—to each region’s unique regulatory and liquidity environments.
Early Adoption Metrics and ProjectionsAt launch, over 150 million merchant acceptance points are ready to process stablecoin-backed transactions without any point-of-sale modifications. The initial six Latin American markets encompass an estimated 60 million potential underbanked and remittance-focused users. Visa processed 232 billion transactions in total during 2023; Bridge targets capturing 0.5 percent of that volume—approximately 1.16 billion stablecoin transactions—by Q4 2025. Bridge’s support for more than 20 stablecoin liquidity pools and market-maker partners aims to keep slippage below 0.5 percent on conversions. Pilot programs project monthly stablecoin transaction volume exceeding $100 million within the first year, and preliminary data indicates cost savings of up to 30 percent versus traditional cross-border foreign-exchange rails in Latin America.
More News: Stablecoin Volume Surges Past Traditional Payment Giants (Visa & Mastercard)
The post Visa and Bridge Partner to Make Stablecoins Accessible for Everyday Purchases appeared first on CryptoNinjas.
Why this matters
This blockchain story adds another data point to the current market tape and is useful when read alongside nearby source coverage.
Original source
Read on CryptoNinjasRelated market context
$55 million Aave stablecoin pool sees just $4.4 million available for withdrawals
Aave's USDT0 stablecoin lending pool on the Monad network displayed a 6.10% annual percentage rate over the weekend, but only abou...
Hackers mint trillions in fake Bitcoin, but 15 BTC bridge recovery leaves liquidity providers unpaid
Cross-chain protocol Symbiosis said it recovered approximately 15 BTC after an attacker exploited its native Bitcoin Bridge, but a...
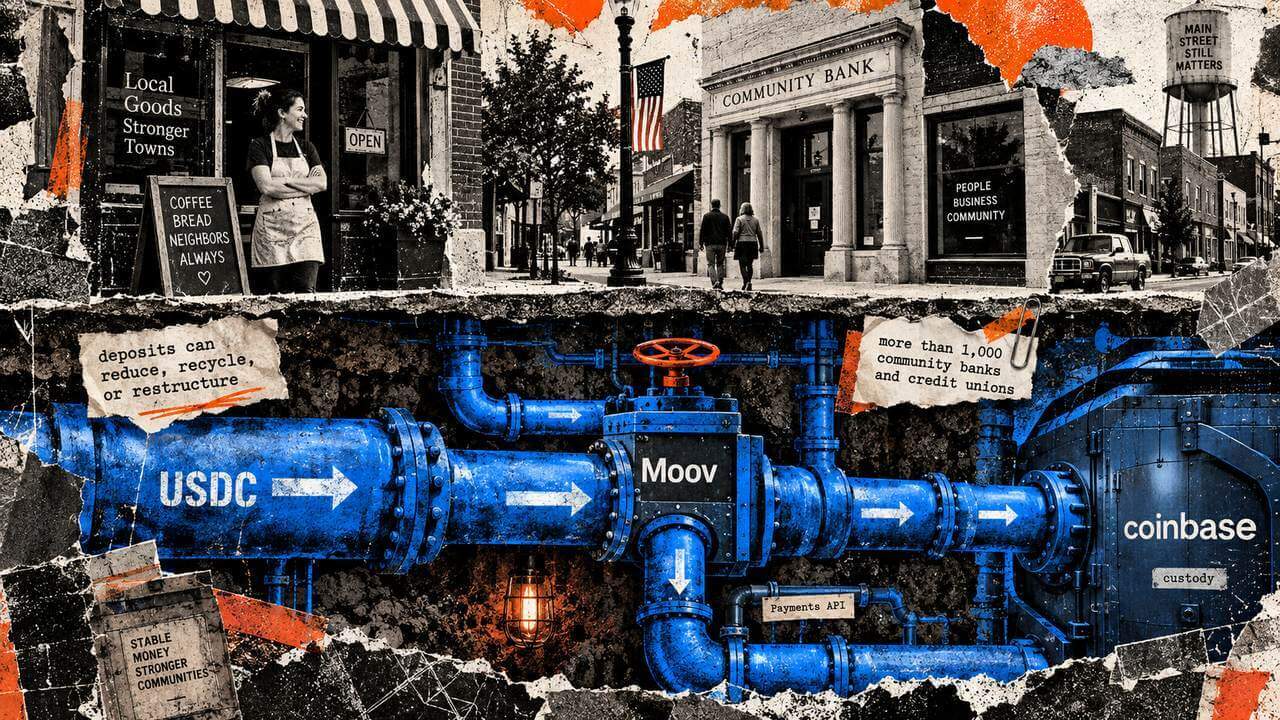
Coinbase gives community banks a stablecoin bridge while supplying infrastructure underneath
Coinbase’s new partnership with payments platform Moov gives community banks and credit unions a route to offer stablecoin service...
Kraken Lets Users Earn DeFi Yield on Nvidia and ETF xStocks
Kraken has launched on-chain yield vaults for three tokenised securities, enabling qualified clients to earn variable rewards from...

Zoth expands zPayments to Base, targeting $6B in annual cross-border stablecoin payouts
Zoth's expansion of zPayments on Base could significantly disrupt traditional cross-border payment systems, enhancing speed and re...
Revolut Crypto Data Leak Exposes Bitcoin Records, Attackers Demand Payment to Stop More
Key Takeaways: Hackers have reportedly begun to share personal data on the affected customers and ask for money to prevent more le...